How Long Does It Take to Buy a House? What Southern Maryland Buyers Should Know
How long does it take to buy a house in Southern Maryland? For most buyers, the process is better measured in stages than by one fixed number of days. You need time to prepare financially, get pre-approved, find the right property, negotiate an offer, complete inspections and financing requirements, and finally make it to closing.
Some buyers find a home almost immediately. Others search for weeks or months before making an offer. Once you're under contract, the timeline becomes more structured, but financing, appraisal, inspections, underwriting, title work, and other transaction details can still affect the closing date.
Whether you're a first-time homebuyer, relocating to Southern Maryland, buying an investment property, or preparing for your next move, knowing what happens at each stage can make the process much easier to navigate.
Maryland's homebuying guidance outlines many of these same stages, including preparing to buy, lender pre-approval, working with a real estate professional, making an offer, completing the loan process, and closing.
How Long Does It Take to Buy a House From Start to Finish?
There is no universal home buying timeline because every buyer and transaction is different.
Think of buying a house as having two separate timelines.
The first is everything that happens before you have an accepted offer. That includes getting financially prepared, obtaining mortgage pre-approval if you're financing, deciding what you need in a home, searching available properties, touring homes, and negotiating an offer.
This stage is difficult to predict. You could find a home you love during your first weekend of house hunting, or it could take several months.
The second timeline begins after your offer is accepted.
At this point, the transaction may involve inspections, due diligence, appraisal, mortgage processing, underwriting, title and settlement preparation, a final walkthrough, and closing.
Because those steps have deadlines and involve multiple professionals, this portion of the transaction is usually more structured. However, the exact timing still depends on your contract, financing, lender, property, and individual transaction.
For buyers trying to plan a move, the important takeaway is simple: don't assume the day you start house hunting determines the day you'll receive your keys.
Step-by-Step Southern Maryland Home Buying Timeline
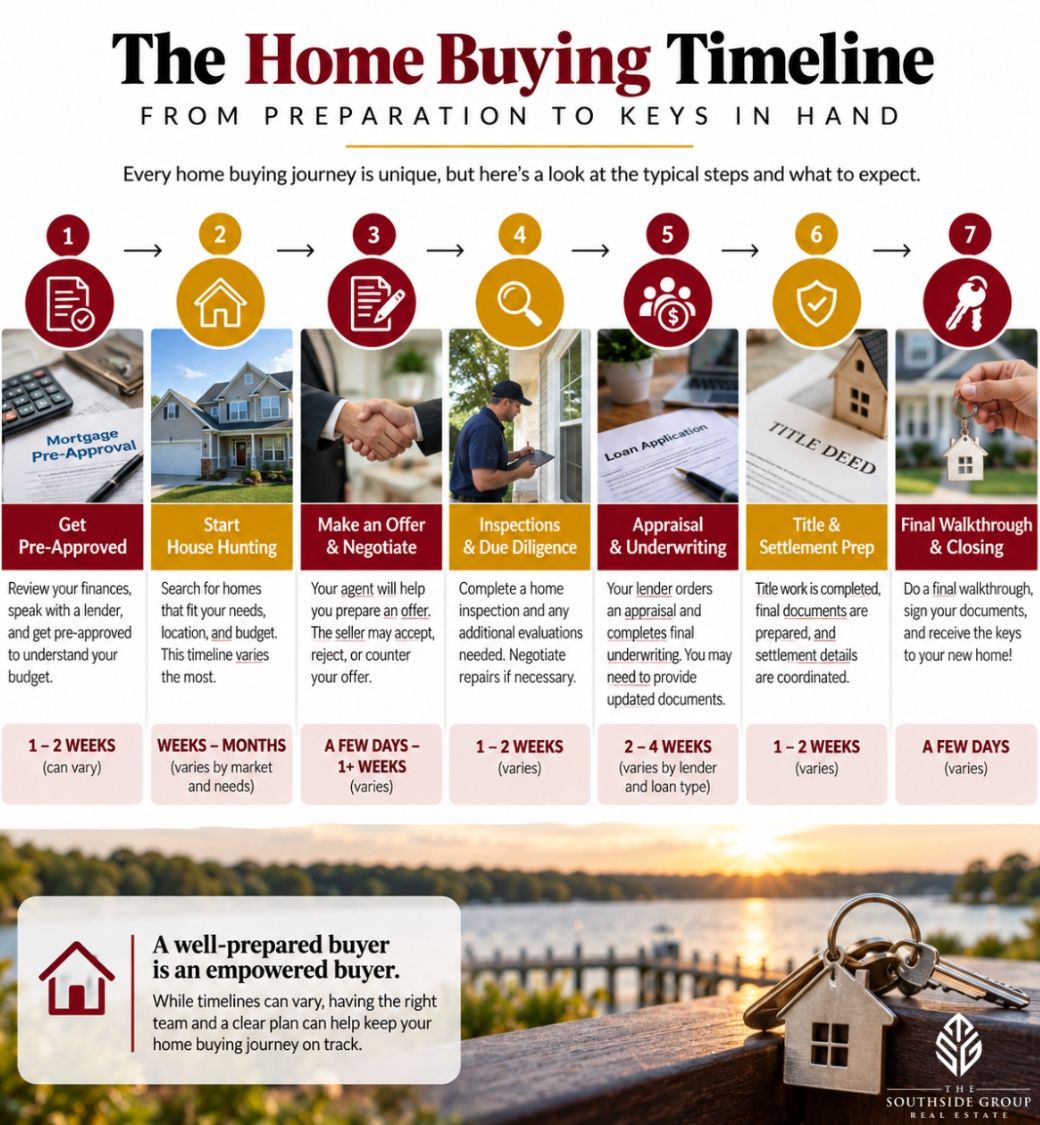
Understanding each stage can help you prepare before you start touring homes in St. Mary's County, Charles County, or Calvert County.
Step 1: Prepare Your Finances and Get Pre-Approved
If you plan to finance your purchase, getting pre-approved is an important early step.
A mortgage lender may review your income, assets, debts, credit history, employment information, and other documentation to determine what financing may be available to you.
Pre-approval also helps you establish a more realistic price range before you spend significant time touring properties.
Maryland Mortgage Program guidance similarly places working with an approved lender and obtaining pre-approval early in the homebuying process.
If you're considering Maryland-specific homebuyer programs, ask your lender about eligibility and current requirements rather than assuming a particular program or benefit applies to your situation.
The sooner you organize important financial documents, the easier it may be to respond when your lender requests updated information later.
Step 2: Find the Right Southern Maryland Home
House hunting is often the biggest wildcard in the entire timeline.
Southern Maryland includes many different housing markets across St. Mary's, Charles, and Calvert counties, and available inventory can vary considerably based on location, price range, property type, and your individual criteria.
Some buyers are flexible about location and home style. Others may need a very specific combination of commute, property features, price, acreage, waterfront access, or other characteristics.
Those differences can dramatically change how long the search takes.
Instead of setting an artificial deadline for finding a house, focus on being ready when an appropriate property becomes available.
That means knowing your budget, understanding your priorities, monitoring new listings, and having a plan for touring homes that interest you.
Step 3: Make an Offer and Negotiate
Finding the house doesn't automatically mean you're under contract.
Your next step is preparing an offer.
The offer involves more than the purchase price. Depending on the transaction, buyers and sellers may negotiate various terms, timelines, and contingencies.
Maryland homebuying guidance notes that a real estate professional can help buyers consider the offer price and contingencies involving matters such as financing, appraisal, and inspection.
The seller may accept your offer, reject it, or propose different terms.
Negotiations might happen quickly, or they may require additional communication before both parties reach an agreement.
Once an agreement is reached and the contract is ratified, you move from house hunting into the under-contract phase.
Read our guide on what happens after your offer is accepted to learn what to expect once you're under contract.
Step 4: Complete Inspections and Due Diligence
Depending on your contract and the property, the next stage may include a home inspection and other forms of due diligence.
An inspection may reveal items that deserve additional evaluation. Depending on the contract and circumstances, that could lead to further investigation, discussions, or negotiations.
This is an important reason not to view the home buying timeline as simply a race to closing.
Buyers need enough time to complete the steps required by their contract and make informed decisions.
Pay close attention to applicable deadlines and communicate promptly with your real estate professional when questions arise.
Learn what to expect during this stage in our guide to home inspections in Maryland so you can better understand the inspection process and make informed decisions before closing.
Step 5: Complete the Appraisal and Mortgage Underwriting
If you're purchasing with a mortgage, your lender continues working on your loan after you go under contract.
The process may include an appraisal, document verification, mortgage processing, and underwriting.
Maryland's homebuying guidance notes that the lender may order an appraisal and conduct updated employment and credit verification before closing.
Underwriting is essentially the lender's detailed review of the loan file before final approval.
This is why buyers should remain responsive even after receiving an initial pre-approval.
Your lender may request updated bank statements, income documentation, explanations, insurance information, or other materials.
The Consumer Financial Protection Bureau advises buyers to stay alert for lender requests and provide the documents needed for underwriting as they approach closing.
Responding quickly won't guarantee a particular closing date, but it can help prevent an avoidable delay caused by missing documentation.
Step 6: Complete Title and Settlement Preparation
While financing is moving forward, title and settlement work also needs to be completed.
This part of the process helps prepare the transaction for the legal transfer of the property.
Maryland buyers have specific rights involving title and settlement services. The Maryland Title Insurance Consumer's Bill of Rights states that buyers have the right to choose their settlement agent and title insurer and receive information about settlement costs.
Your particular transaction may involve additional requirements, so ask questions when you're unsure what a document, deadline, or request means.
Step 7: Complete the Final Walkthrough and Closing
You're almost there.
Shortly before settlement, buyers typically conduct a final walkthrough.
This is an opportunity to check the property's condition before completing the purchase and confirm that applicable agreed-upon items have been addressed.
The CFPB recommends completing the walkthrough before signing closing documents and checking that agreed repairs and items are in place.
Then comes closing, also called settlement.
You'll complete the required documents associated with the purchase and, when applicable, the mortgage. For financed purchases, the mortgage closing and home purchase closing generally happen together.
Once the transaction is completed according to the applicable requirements, you've reached the moment buyers have been working toward: becoming the owner of the home.
How Long Does It Take to Close on a House After an Offer Is Accepted?
This question is slightly different from asking how long it takes to buy a house.
The overall home buying process begins before you've found a property. The closing timeline generally refers to what happens after you're under contract.
A financed transaction usually has several lender-related steps to complete, including processing, appraisal, underwriting, verification, and preparation for closing.
A cash transaction removes mortgage underwriting from the equation, which may make a faster transaction possible. But paying cash does not automatically mean a buyer can close immediately.
Inspections, title work, contract terms, settlement preparation, seller circumstances, and property-specific issues can still affect timing.
Rather than relying on a generic online average, ask your lender and real estate professional what needs to happen in your particular transaction and which deadlines are established in your contract.
What Can Delay Buying a House?
Even well-prepared buyers can encounter delays because purchasing a home involves multiple people and processes.
Potential delays can include lender requests for additional documentation, financing complications, appraisal concerns, inspection findings, further negotiations, title matters, insurance issues, scheduling conflicts, or property-specific circumstances.
Some issues are outside a buyer's control. Others can be reduced through preparation.
Keep important financial documents organized. Respond promptly when your lender or agent needs information. Monitor your transaction deadlines. Ask questions early rather than waiting until closing approaches.
If you're financing your purchase, it's also wise to communicate with your lender before making significant financial changes while the loan is being processed.
For example, taking on new debt or making other significant financial moves could potentially affect information your lender considers during the mortgage process. Maryland guidance notes that lenders may conduct updated employment and credit verification before closing.
The goal isn't simply to make everything happen faster.
It's to avoid preventable delays while protecting the time you need to make informed decisions.
What Is the Fastest You Can Buy a House?
What is the fastest you can buy a house? There isn't one minimum timeline that applies to every purchase.
A particularly fast transaction may be possible when a buyer is financially prepared, finds a suitable property immediately, reaches an agreement quickly, and the remaining pieces of the transaction line up without complications.
Cash buyers may sometimes have an opportunity to close faster because there is no mortgage underwriting process.
But even a cash transaction can require time for title work, inspections or due diligence when applicable, settlement preparation, contract requirements, and coordination between the parties.
For financed purchases, lenders have their own steps and requirements that must be completed.
If you're a first-time buyer, don't feel pressured to measure success by how quickly you can get from a showing to the closing table.
A better question is:
“How can I be ready to move forward when I find the right home?”
Preparation can be much more valuable than trying to force an important purchase into the shortest possible timeline.
How Long Does It Take to Buy a House in Southern Maryland?
The homebuying process is similar throughout Maryland, but your timeline can vary depending on your budget, property preferences, and location.
Buyers searching in St. Mary's County, Charles County, or Calvert County may encounter different inventory and property options. Your search could also look different depending on whether you're considering Hollywood, Leonardtown, Waldorf, La Plata, Lexington Park, Mechanicsville, or California.
Rather than relying on a fixed timeline, focus on preparing financially, getting pre-approved, defining your priorities, touring homes, making an offer, and completing the steps required to close.
If you're relocating to Southern Maryland, allow extra time to explore communities, compare commute options, and coordinate your move. Preparing early can help you make confident decisions when the right property becomes available.
Why Work With a Southern Maryland Real Estate Expert?
Buying a home involves more than finding a property. You'll need to navigate offers, contract deadlines, inspections, financing, appraisal, and settlement preparation.
A real estate team familiar with St. Mary's County, Charles County, and Calvert County can help you understand the local market, stay informed throughout the transaction, and navigate each stage of the process.
If you're looking for experienced real estate agents in Southern Maryland, our team is here to help you take the next step with practical guidance and local market knowledge.
Start your Southern Maryland home search or contact our team to discuss your homebuying goals.
Ready to Start Your Homebuying Journey?
The time it takes to buy a house depends on how quickly you prepare, find the right property, negotiate an offer, and complete the requirements for closing.
Start by organizing your finances, understanding your priorities, and learning about the Southern Maryland market. With the right preparation and professional guidance, you'll be better equipped to navigate the process from your initial search to closing day.
Explore our Southern Maryland buyer resources to help you prepare for your next move.
FROM OUR BLOG
How to Follow Up With Real Estate Leads Without Being Pushy
Following up with real estate leads can feel like a balancing act. You want to stay connected, answer questions, and turn conversations into appointments. But you also don't want potential clients to feel pressured or overwhelmed by constant calls, texts, and emails. The good news? Effective real es
Best Tacos & Mexican Food Trucks in Southern Maryland
Best Tacos & Mexican Food Trucks in Southern Maryland are worth adding to your local must-try list whether you’ve lived here for years, just bought your first home, or are spending a weekend getting to know the area before a move. Southern Maryland may be famous for Chesapeake Bay seafood, but our l
First-Time Home Buyer Programs in Southern Maryland: 2026 Guide
Buying your first home can feel more achievable once you understand the financing and assistance programs available to you. For buyers in St. Mary’s, Calvert, and Charles counties, several Southern Maryland first-time home buyer programs may help with down payments, closing costs, student loan debt,