Mortgage Pre-Approval in Southern Maryland
Navigate the mortgage process with greater confidence, explore your financing options and take the first step toward securing your ideal Southern Maryland property.
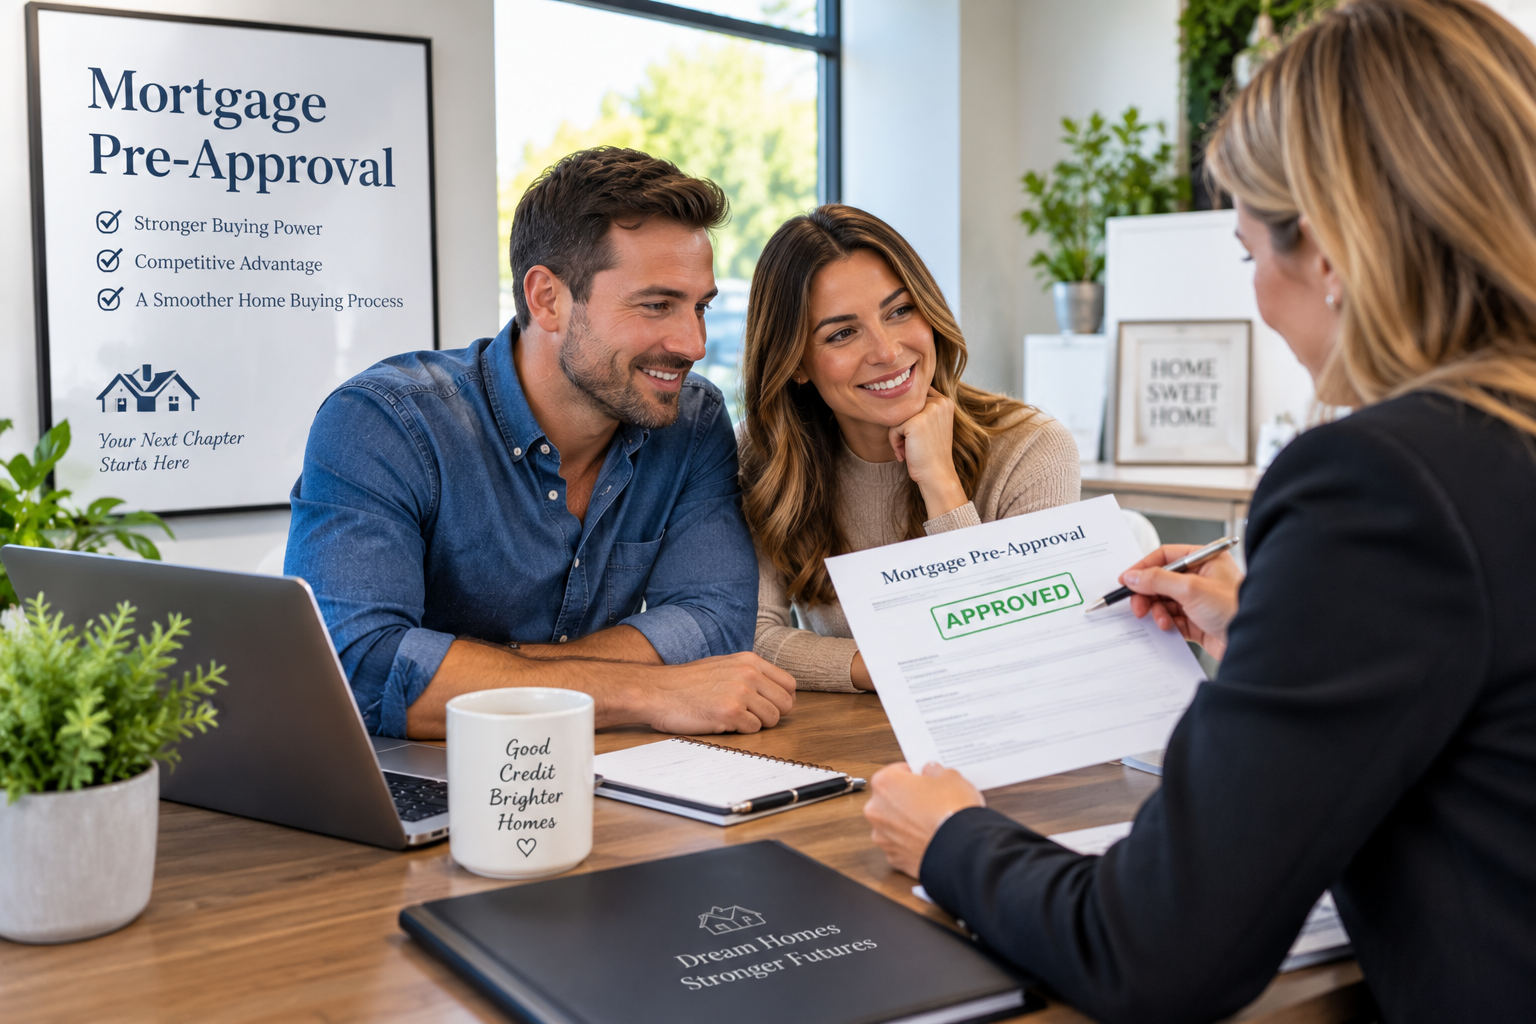
What Is a Mortgage Pre-Approval?
A mortgage pre-approval is a lender’s preliminary review of your financial qualifications for a home loan. Depending on the lender, this typically involves reviewing information such as your:
Income & Employment
Credit History
Current Debts
Bank Accounts & Assets
Down Payment & Closing Costs
Based on that information, the lender may provide a pre-approval letter indicating the loan amount for which you may currently qualify.
A pre-approval is not a guarantee of final mortgage approval. Final approval generally depends on updated financial verification, underwriting, the property, appraisal and other requirements associated with your loan program. Not sure what a mortgage term means? Explore our Financial Terms Glossary.
Why Get Pre-Approved Before Looking at Southern Maryland Homes?
Getting pre-approved before seriously touring homes gives you useful information before you make a major financial decision.
Understand Your Home-Buying Budget
Your lender can help estimate how much you may qualify to borrow and what your potential monthly payment could look like.
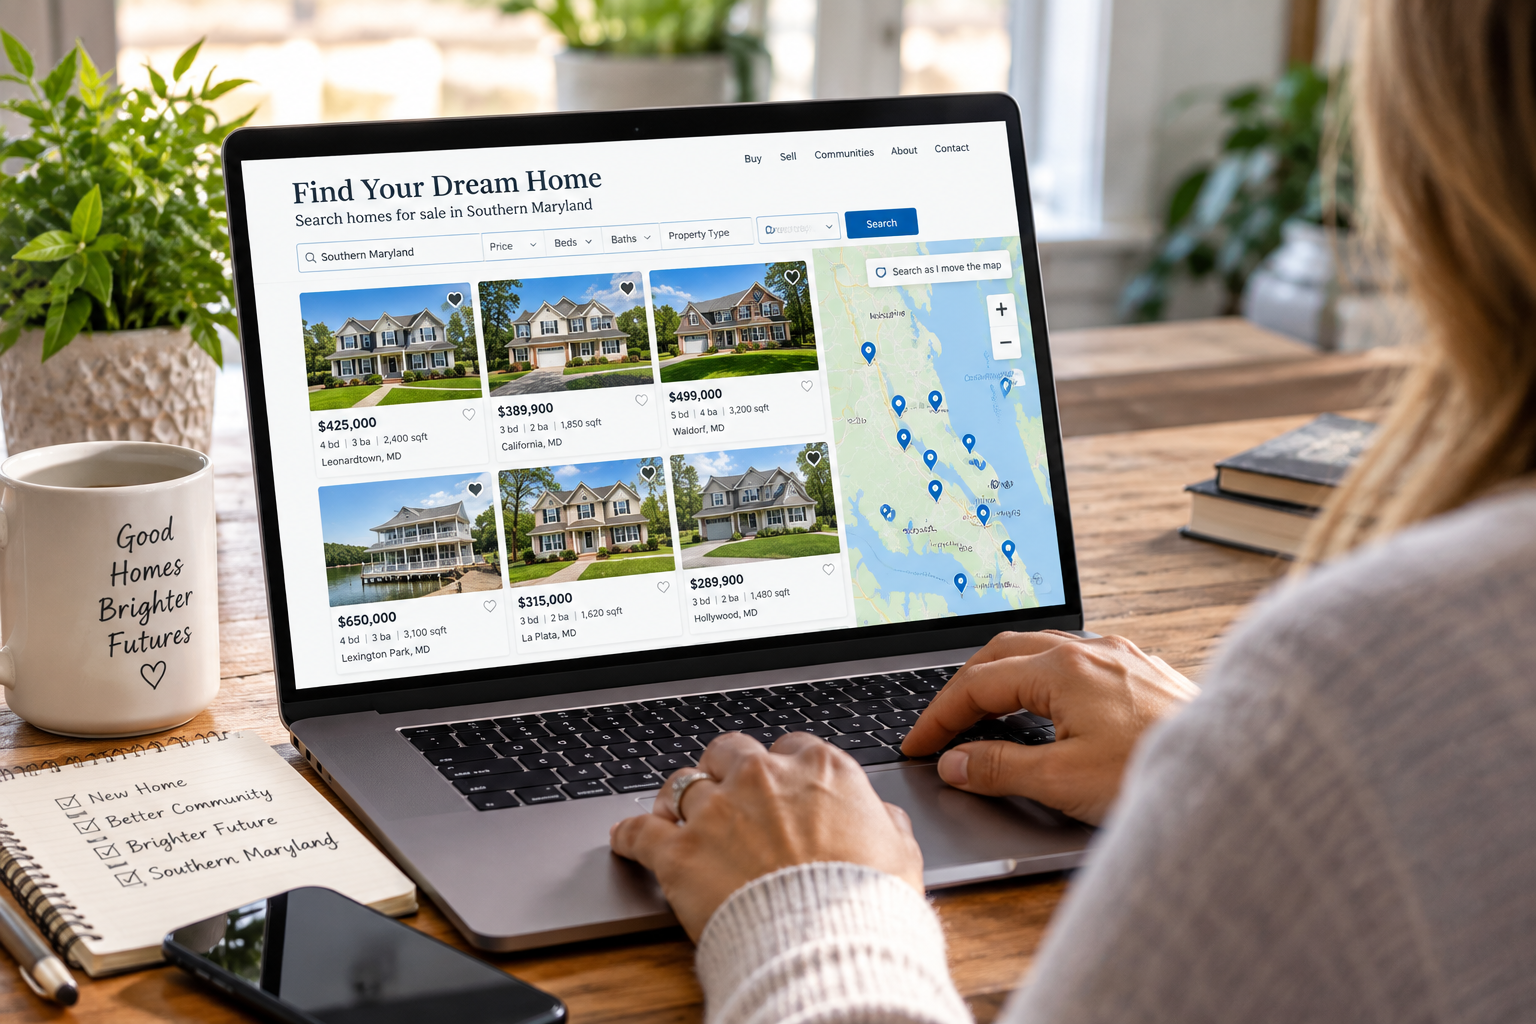
That allows you and your real estate agent to focus your search on Southern Maryland homes for sale that better align with your financing and budget.
Be Better Prepared to Make an Offer
When you find a home you want to purchase, you may need to move quickly. Having your financing documents prepared can reduce delays between finding the property and submitting an offer.
A current pre-approval letter can also demonstrate to a seller that you have already started the mortgage qualification process.
Identify Financing Issues Early
Speaking with a lender before you begin your home search may uncover issues that need attention, such as credit concerns, debt-to-income considerations, documentation requirements or the amount of cash needed for closing.
Discovering those issues early gives you more time to understand your options.
Mortgage Options for Southern Maryland Home Buyers
There is no single mortgage program that works for every buyer. Your lender should evaluate your finances, property plans and eligibility before recommending a specific loan.
Depending on your circumstances, financing options may include:
Conventional Loans
Conventional mortgages are commonly used by Southern Maryland home buyers and are not insured or guaranteed by a federal government agency.
Down-payment requirements, private mortgage insurance, credit standards and pricing can vary by lender and loan product.
FHA Loans
FHA-insured mortgages can provide another financing option for qualified home buyers. FHA's basic home mortgage program permits approximately 96.5% financing for eligible borrowers, although borrowers are also responsible for applicable mortgage insurance premiums.
Ask your lender to explain the complete cost of FHA financing rather than evaluating the loan based only on the down payment.
VA Home Loans
Southern Maryland is home to many military-connected households, making VA home financing particularly relevant to eligible local buyers.
VA-backed purchase loans are available to qualifying Veterans, service members and certain surviving spouses. Eligibility involves VA requirements as well as lender standards, and borrowers generally need a Certificate of Eligibility. VA-backed financing may allow eligible borrowers to purchase without a down payment, although lender requirements and individual circumstances still apply.
USDA Loans
Some buyers searching outside Southern Maryland’s more developed areas may want to ask their lender about USDA financing.
Eligibility depends on factors including the borrower, household circumstances, loan requirements and the location of the property. A lender familiar with USDA financing can determine whether a particular buyer and property may qualify.
How Much Home Can You Comfortably Afford?
The amount a lender is willing to approve and the amount you are comfortable spending are not necessarily the same.
When establishing your home-buying budget, consider the total monthly housing expense, which may include:
- Mortgage principal and interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, when applicable
- HOA or condominium fees, when applicable
- Other property-specific expenses
You should also account for expenses beyond the mortgage, including maintenance, utilities, and your other financial goals.
This becomes especially important when comparing different types of Southern Maryland properties. A waterfront property, condominium, larger home, property with acreage, or older home may have different ongoing ownership expenses.
Choose a budget that works for your finances—not simply the maximum amount you can borrow.
Documents You May Need for Mortgage Pre-Approval
Every lender and borrower situation is different, but preparing your financial records ahead of time can make the process more efficient.
Your lender may request documents such as recent pay statements, W-2s or tax returns, bank and asset statements, identification, employment information and documentation related to other income or financial obligations.
Self-employed borrowers and buyers with more complex income sources may need additional documentation.
Your lender should provide the exact documentation requirements for your application.
Compare Mortgage Lenders and Loan Offers
You are free to choose your mortgage lender, and comparing options can be worthwhile.
Do not compare lenders based solely on the advertised interest rate. Ask about:
- Interest rate and APR
- Loan type and term
- Discount points
- Origination and lender fees
- Mortgage insurance
- Estimated closing costs
- Rate-lock options
- Estimated cash needed at closing
- Communication and processing timelines
For VA financing specifically, the VA notes that rates and fees can vary among lenders and recommends shopping around.
The Southside Group Real Estate can provide contacts based on past transaction experience, but the choice of lender and financing program remains yours.
Mortgage Pre-Approval FAQ
Does mortgage pre-approval guarantee I will receive the loan?
No. A pre-approval is preliminary and is not a commitment that the mortgage will receive final approval. Your lender must still complete its underwriting and property-related requirements.
Should I get pre-approved before looking at homes?
How much should I get pre-approved for?
Can I use a VA loan to buy a home in Southern Maryland?
Are FHA loans available for Southern Maryland homes?
Can I choose my own mortgage lender?
What is the difference between pre-qualification and pre-approval?