You found a home you love in Southern Maryland, submitted an offer, and now you're being asked about an earnest money deposit.
What exactly is earnest money? Where does the money go? Does it become part of your down payment? And perhaps most importantly, can you get it back if the home purchase doesn't work out?
Earnest money is essentially a good-faith deposit connected to your contract to purchase a home. It demonstrates to the seller that you're serious about completing the transaction.
But earnest money isn't something buyers should treat casually.
Whether the deposit is returned, credited at closing, or potentially forfeited depends on the purchase contract, what happens during the transaction, and whether the parties meet their contractual obligations.
Here's what Southern Maryland buyers should understand before making an offer.
What Is Earnest Money in Real Estate?
Earnest money is money a buyer deposits in connection with an accepted contract to purchase a property.
You may also hear it called an:
- Earnest money deposit
- Good-faith deposit
- EMD
- Contract deposit
The deposit demonstrates that the buyer has a financial commitment to the transaction.
Imagine a seller accepts your offer and takes the property off the market. During the following weeks, the seller may stop actively pursuing other buyers while you complete financing, inspections, appraisal, title work, and other steps required by the contract.
Earnest money gives the buyer some financial commitment to completing the transaction according to the agreement.
It is important to understand, however, that earnest money is not simply a fee paid to the seller.
If the transaction closes normally, the deposit is generally credited toward the purchase transaction.
How Does Earnest Money Work?
Although every transaction and contract can be different, the basic process generally looks like this:
You Make an Offer
Your purchase offer identifies the proposed purchase price and other important terms.
Those terms can include the amount of the earnest money deposit and requirements governing when it must be delivered.
The Seller Accepts the Contract
Once the parties have an accepted contract, the buyer must follow the contract's requirements for delivering the earnest money.
Pay particular attention to the deadline. A buyer shouldn't assume the money can simply be delivered whenever it's convenient.
The Earnest Money Is Held
The money is generally held according to the purchase agreement and applicable law rather than becoming spending money for the seller.
In Maryland transactions involving trust money held by a real estate broker, state law establishes requirements governing how that money is maintained and eventually distributed.
The Transaction Moves Toward Closing
The buyer and seller continue fulfilling their obligations under the contract.
For the buyer, that may involve financing, inspections, appraisal, reviewing property information, and completing other due-diligence requirements.
The Deposit Is Addressed at Closing
If the transaction successfully closes, the buyer's earnest money is generally credited toward the transaction.
That means the money doesn't simply disappear.
Does Earnest Money Go Toward the Down Payment?
Earnest money can generally be credited toward the amount you owe as part of the purchase transaction, including the down payment or closing costs as applicable.
Here's a simplified example.
Suppose you're buying a Southern Maryland home for $400,000.
You provide a $5,000 earnest money deposit after your offer is accepted.
Later, your final closing figures show that you need to bring $25,000 to closing before accounting for that deposit.
If the $5,000 deposit is properly credited toward your cash-to-close amount, you would generally need to provide the remaining $20,000, assuming there are no other adjustments.
This is only a simplified illustration. Your lender and settlement professional will determine your actual cash-to-close amount.
The important distinction is this:
Earnest money and a down payment are not the same thing.
Your earnest money is a deposit made during the purchase process.
Your down payment is the portion of the home's purchase price you're paying rather than financing.
The earnest money can ultimately be credited toward the money you need for the transaction.
How Much Earnest Money Do You Need?
There is no universal earnest money amount that applies to every home purchase.
National consumer guidance commonly describes earnest money as a percentage of the purchase price, but the actual amount depends on the transaction, contract, local market, property, competition, and offer strategy.
For example:
|
Purchase Price |
1% |
2% |
3% |
|
$300,000 |
$3,000 |
$6,000 |
$9,000 |
|
$400,000 |
$4,000 |
$8,000 |
$12,000 |
|
$500,000 |
$5,000 |
$10,000 |
$15,000 |
|
$600,000 |
$6,000 |
$12,000 |
$18,000 |
These figures are examples—not recommendations for what you should offer.
In some situations, the appropriate deposit could be below or above these examples.
That's why a Southern Maryland buyer should determine earnest money as part of the overall offer strategy, rather than automatically choosing a percentage.
Does More Earnest Money Make an Offer Stronger?
Potentially.
A larger earnest money deposit can communicate that a buyer is serious about completing the transaction.
That can matter when a seller is evaluating multiple offers.
But bigger isn't automatically better.
Earnest money is real money that may be subject to the terms of your contract. Increasing the deposit simply to make an offer appear stronger can expose more of your money if a dispute develops or you fail to perform according to the agreement.
A strong offer should therefore be evaluated as a whole.
That includes factors such as:
- Purchase price
- Financing
- Earnest money
- Settlement timeline
- Contingencies
- Requested seller concessions
- Property-specific terms
- Buyer's ability to perform
The goal isn't necessarily to offer the largest earnest money deposit.
The goal is to create an offer that is competitive while keeping the buyer informed about the financial and contractual implications.
Is Earnest Money Refundable?
It can be.
But there is an important distinction between saying earnest money can be refundable and saying it is always refundable.
Whether a buyer is entitled to the deposit depends heavily on the purchase contract and circumstances surrounding the termination of the transaction.
A contract may contain conditions or contingencies that give a buyer certain termination rights.
Depending on the agreement, these could involve issues such as:
- Financing
- Appraisal
- Property inspections
- Sale of another property
- Title
- Other contract-specific conditions
If the buyer properly terminates the contract under a contractual right that provides for the return of the deposit, the buyer may be entitled to receive the earnest money back.
But buyers shouldn't assume that simply deciding they no longer want the property automatically means the deposit will be returned.
When Could a Buyer Lose Earnest Money?
A buyer may risk losing earnest money when the buyer fails to perform as required by the contract or terminates the transaction without a contractual basis protecting the deposit.
For example, imagine a buyer has an accepted contract but later decides:
"I found another house I like better."
Whether that buyer can simply terminate the first contract and recover the earnest money isn't something that can be answered without examining the agreement.
The same concern can arise when a buyer:
- Misses important contractual deadlines
- Fails to make required efforts toward financing
- Does not deliver required funds
- Terminates after contractual protections have expired
- Otherwise fails to perform under the agreement
This is why buyers should understand deadlines and contingencies before signing, not after a problem develops.
What Happens to Earnest Money if the Home Inspection Finds Problems?
It depends on the contract.
A home inspection doesn't automatically guarantee that a buyer can cancel a purchase and receive the earnest money back.
The buyer's rights depend on the inspection provisions contained in the agreement and whether the buyer follows those provisions correctly.
Depending on the contract, inspection findings could lead to further negotiations, requests for repairs or credits, acceptance of the property, or termination.
The key is to understand your contractual rights and deadlines before taking action.
What Happens if the Home Doesn't Appraise?
Again, look at the contract.
When a buyer is financing a home, the lender generally orders an appraisal to help determine the property's value for lending purposes.
If the appraisal comes in below the purchase price, what happens next depends on the financing, appraisal provisions, contract terms, and decisions of the parties.
Possible outcomes can include:
- Buyer and seller renegotiating the price
- Buyer contributing additional funds
- Seller adjusting terms
- Buyer exercising an applicable contractual right
- Transaction continuing under previously negotiated terms
- Transaction terminating
A low appraisal by itself shouldn't be interpreted as an automatic guarantee that earnest money will be refunded.
What Happens to Earnest Money if Financing Falls Through?
The answer depends on the financing provisions of the contract and whether the buyer complied with them.
A properly structured financing contingency may provide protections when a buyer cannot obtain the required financing despite making the efforts required under the agreement.
But simply having a mortgage involved doesn't necessarily mean the buyer can cancel at any time without consequences.
Buyers should understand:
- Financing deadlines
- Loan-application requirements
- Documentation requirements
- Loan type
- Financing contingency
- Required notices
- Any other financing-related obligations in the contract
If you're planning to finance your purchase, getting mortgage pre-approved before making offers can help you better understand your financing position.
What Happens to Earnest Money in Maryland?
This is where local knowledge becomes especially important.
Maryland has specific requirements governing trust money held by real estate brokers.
Under Maryland law, a real estate broker generally must maintain trust money in an authorized account until one of the circumstances permitted by law occurs.
Those circumstances include the transaction being consummated or terminated, proper written instructions regarding disposition of the money, certain court orders, or other circumstances addressed by Maryland law.
This matters because buyers sometimes assume:
"The contract was canceled, so the broker can immediately send my deposit back."
It may not be that simple.
If the buyer and seller disagree over who is entitled to the earnest money, the broker holding the funds may not simply choose a side and immediately release them.
Maryland law provides procedures governing how broker-held trust money can be handled.
A deposit dispute can therefore be much more complicated than simply asking the real estate agent to return the money.
For a dispute involving contractual or legal rights, buyers and sellers should consider obtaining advice from a qualified Maryland real estate attorney.
Want to Know More About Maryland’s Earnest Money Rules?
If you’re dealing with a disputed or delayed earnest money deposit, it’s important to understand the rules that govern how those funds may be handled. The Maryland Real Estate Commission provides additional information on the return of deposits and the procedures that may apply.
👉 Learn More About Maryland Earnest Money Deposits
Understanding the process can help you know what to expect and what steps may be available if your deposit is being held.
Who Holds Earnest Money in a Maryland Real Estate Transaction?
The contract should identify how the deposit will be handled.
Depending on the transaction, earnest money may be held in an appropriate escrow or trust arrangement.
When trust money is entrusted to a Maryland real estate broker, state law governs the broker's handling of those funds.
Buyers should know:
- Who is holding the deposit
- How much is being deposited
- When it must be delivered
- What form of payment is required
- What the contract says about its disposition
Never assume these details.
Read the agreement.
What Happens to the Buyer's Earnest Money at Closing?
Suppose you're buying a home in Southern Maryland and your accepted purchase contract requires an earnest money deposit.
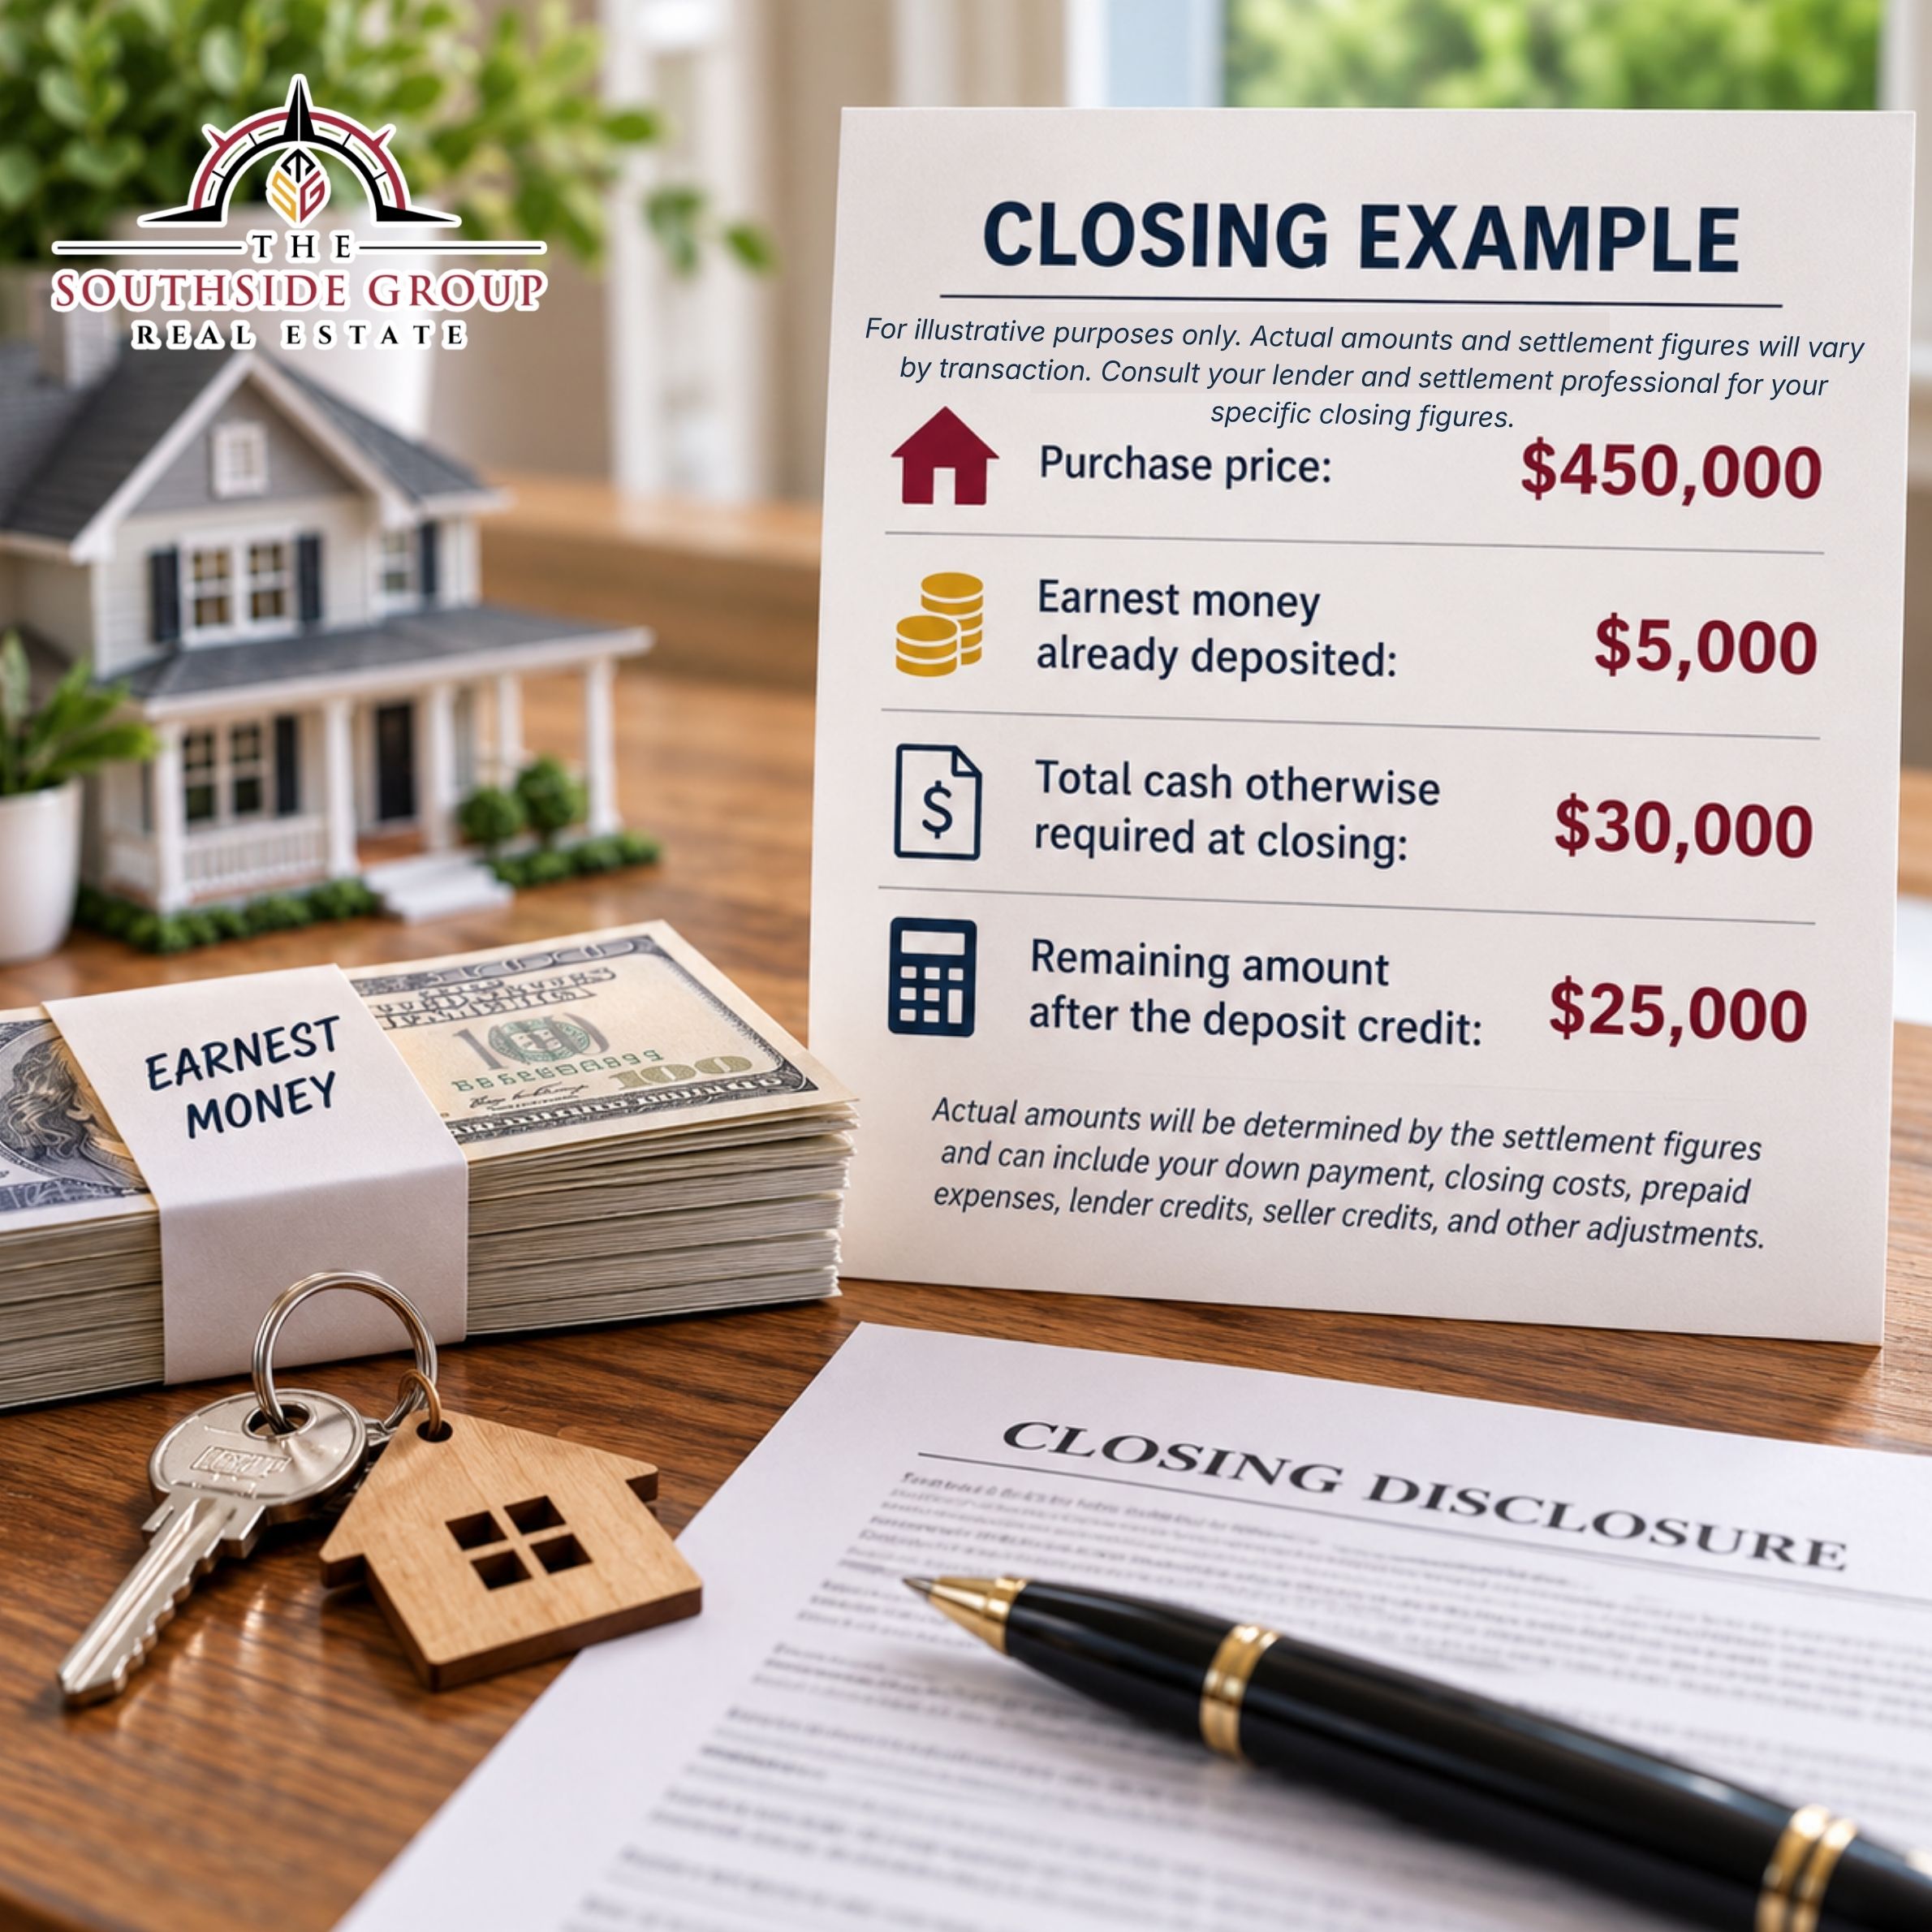
If the transaction moves forward successfully to settlement, the earnest money you've already deposited is generally credited toward the purchase, which can reduce the additional amount you need to bring to closing.
For example:
Purchase price: $450,000
Earnest money already deposited: $5,000
Total cash otherwise required at closing: $30,000
Remaining amount after the deposit credit: Approximately $25,000
In this example, the buyer isn't paying an additional $5,000 on top of the $30,000. The earnest money already deposited is accounted for in the transaction, leaving approximately $25,000 remaining.
The actual amount required at settlement will depend on the final closing figures and may include the buyer's down payment, closing costs, prepaid expenses, lender credits, seller credits, and other adjustments.
What If the Transaction Doesn't Close?
If an issue arises and the buyer wants to terminate the contract, the earnest money is not automatically returned simply because the buyer decides not to purchase the home.
Whether the deposit is returned can depend on the terms of the purchase contract, the reason for termination, applicable contingencies and deadlines, whether contractual requirements were satisfied, and Maryland law governing the handling of the deposit.
For buyers purchasing a home in Southern Maryland, including St. Mary's County, Calvert County, and Charles County, earnest money should be viewed as an important part of the overall purchase contract—not simply another upfront expense.
Is Earnest Money the Same as a Down Payment?
No.
This is a common point of confusion for first-time home buyers.
Earnest money is the good-faith deposit associated with the purchase contract.
Down payment is the portion of the purchase price you pay rather than finance.
Closing costs are expenses associated with obtaining the loan and completing the transaction.
These are separate concepts, although your earnest money can ultimately be credited toward the funds required at closing.
Is Earnest Money the Same as a Security Deposit?
No.
A security deposit is commonly associated with renting property.
Earnest money is associated with a contract to purchase real estate.
Although both involve deposits, they serve different purposes and are governed by different agreements and legal requirements.
How Can Buyers Protect Their Earnest Money?
The best protection begins before the contract is signed.
Understand the Contract
Don't focus exclusively on the purchase price.
Know what the agreement says about your deposit, contingencies, deadlines, notices, and termination rights.
Track Every Deadline
Real estate contracts can contain multiple deadlines.
Missing one can affect your rights.
Your agent should help you track important dates, but you should understand them as well.
Don't Waive Protections Without Understanding the Risk
Competitive markets can tempt buyers to remove contingencies or offer aggressive terms.
That may strengthen an offer, but it can also increase risk.
Understand the consequences before agreeing to those terms.
Keep Your Financing Moving
If you're financing the purchase, promptly provide your lender with requested documents and information.
Avoid making major financial changes without first discussing them with your lender.
Keep Documentation
Maintain records related to your deposit, contract, notices, financing, inspections, and other transaction documents.
Ask Questions Before Signing
If you don't understand when your earnest money could be returned or forfeited, ask before committing to the contract.
For legal interpretation of your rights and obligations, consult a qualified attorney.
Buying a Home in Southern Maryland?
Earnest money may look like a relatively small part of buying a house, but it connects directly to some of the most important parts of your offer: your financial commitment, contingencies, deadlines, and contractual protections.
Before deciding how much earnest money to offer on a Southern Maryland home, understand both the competitive advantage and potential risk.
The Southside Group Real Estate helps buyers navigate the home-buying process throughout St. Mary's County, Calvert County, and Charles County, from preparing to make an offer through settlement.
If you're considering buying a home, start by understanding your budget, financing, target communities, and offer strategy before the right property hits the market.
Explore homes for sale in Southern Maryland or contact The Southside Group Real Estate to start planning your home purchase.
FROM OUR BLOG
Calvert County Community Events | September 18–20, 2026
Calvert County events are filling the weekend of September 18–20, 2026, with art festivals, waterfront celebrations, local food, live entertainment, markets, history, outdoor activities, and plenty of opportunities to explore Southern Maryland. If you’re searching for things to do in Calvert County
Charles County Community Events | September 18–20, 2026
Charles County events are filling the calendar September 18–20, 2026, with the county fair, local markets, community celebrations, family activities, food, entertainment, and plenty of reasons to get out and explore Southern Maryland. If you’re searching for things to do in Charles County this weeke
St. Mary’s County Community Events | September 18–20, 2026
St. Mary’s County events are filling the calendar for September 18–20, 2026, with food, live entertainment, historic experiences, outdoor activities, cars, community gatherings, and plenty of reasons to get out and explore Southern Maryland. If you’re searching for things to do in St. Mary’s County