If you're planning to buy a home, one of the first questions you may have is: How much should I save before buying a house?
The answer isn't simply 20% of the purchase price.
Your savings plan should account for your down payment, closing costs, moving expenses, potential inspections and upfront expenses, and money you want to keep available after closing.
For buyers considering a home in Southern Maryland—including St. Mary's County, Calvert County, and Charles County—the right savings target will depend on your price range, loan program, financial situation, and the property you're purchasing.
Here's how to start calculating what you may need.
How Much Money Do You Need to Buy a House in Maryland?
There isn't one savings amount that every Maryland home buyer needs.
A better way to approach the question is to divide your savings goal into several categories:
-
Down payment
-
Closing costs
-
Inspections and other transaction-related expenses
-
Moving expenses
-
Immediate repairs or purchases
-
Emergency savings
-
Additional cash reserves that may be required for your financing
Your mortgage program can make a significant difference.
Some qualified borrowers may have access to mortgage options requiring a relatively small down payment, while other buyers may choose to put substantially more down.
The Consumer Financial Protection Bureau notes that, in most cases, buyers need at least 3% of their target purchase price as a down payment, although many loan types and lenders require 5% or more.
That means you should not automatically assume that you need 20% down before you can begin looking at homes.
Do You Need 20% Down to Buy a House?
No. A 20% down payment is not a universal requirement for purchasing a home.
Different mortgage programs have different requirements.
For example:
Conventional Loans
Some conventional mortgage programs allow qualified buyers to purchase with down payments as low as 3%.
The exact amount you need will depend on the mortgage product, lender requirements, your qualifications, and other factors.
When a conventional buyer puts less than 20% down, private mortgage insurance may be required.
FHA Loans
FHA-insured mortgages can allow a minimum down payment of 3.5% for borrowers with qualifying credit scores of 580 or higher.
FHA loans have additional requirements and mortgage insurance considerations, so buyers should discuss the complete cost of the loan with a qualified lender.
VA Loans
Eligible veterans, active-duty service members, and certain surviving spouses may have access to VA financing that can provide significant home-buying advantages, including the possibility of purchasing without a traditional down payment.
This can be particularly relevant in Southern Maryland because of the area's military community and proximity to installations such as Naval Air Station Patuxent River and Joint Base Andrews.
Eligibility and the complete cost of financing should be reviewed with a VA-approved lender.
USDA Loans
Eligible buyers purchasing an eligible property may also qualify for USDA Rural Development financing.
USDA's Single Family Housing Guaranteed Loan Program provides 100% financing for qualified borrowers purchasing eligible properties, meaning a traditional down payment may not be required.
Property location, household income, occupancy, and other eligibility requirements apply.
How Much Should You Save for Closing Costs?
Your down payment is only part of the money you may need.
You should also prepare for closing costs.
The Consumer Financial Protection Bureau says closing costs typically range from approximately 2% to 5% of the home's purchase price, separate from your down payment.
Actual closing costs vary based on factors including:
-
Purchase price
-
Loan type
-
Lender
-
Property
-
Location
-
Title and settlement expenses
-
Taxes and government charges
-
Homeowners insurance
-
Prepaid interest
-
Initial escrow requirements
-
Other transaction-specific expenses
This is one reason buyers should be careful about putting every available dollar toward their down payment.
You still need enough money to complete the transaction—and ideally some savings remaining afterward.
How Much Down Payment Do I Need for a $300,000 House?
Let's use a $300,000 home as a simple example.
Your down payment could look approximately like this:
| Down Payment | Amount on a $300,000 Home |
|---|---|
| 3% | $9,000 |
| 3.5% | $10,500 |
| 5% | $15,000 |
| 10% | $30,000 |
| 20% | $60,000 |
But down payment is not the same as total cash needed to buy the house.
If you used a hypothetical 5% down payment, for example, the down payment would be $15,000.
Then you would need to consider closing costs and the other expenses associated with your purchase.
Using the CFPB's broad 2%–5% closing-cost range for illustration, closing costs on a $300,000 purchase could potentially represent approximately $6,000–$15,000.
That would put the hypothetical combination of a 5% down payment and estimated closing costs at approximately $21,000–$30,000, before considering moving expenses, inspections, repairs, furnishings, or the emergency savings you want to retain.
This is an illustration—not a quote or prediction of what your actual purchase will cost. Your lender and settlement professionals can provide estimates based on your specific transaction.
Is $20,000 Enough to Buy a House?
Possibly.
The more useful question is:
What can $20,000 accomplish based on my loan program, home price, closing costs, and required reserves?
Suppose you have $20,000 saved.
It may be enough to cover the upfront costs of certain purchases when combined with an eligible low-down-payment loan, assistance program, seller contribution, lender credit, or other permitted source of funds.
In another situation, $20,000 might not be sufficient.
That's why buyers should avoid treating a specific savings number as a universal threshold.
Instead, ask a lender to estimate the cash to close for the price range and loan programs you're considering.
Then determine how much money you want to have remaining after the transaction.
Don't Forget About Your Emergency Fund
One of the biggest mistakes a buyer can make is focusing so heavily on getting the keys that there is almost nothing left in savings afterward.
The CFPB recommends subtracting an emergency cushion when determining how much of your available savings can be used toward a purchase and describes three to six months of expenses as a useful rule of thumb.
Why?
Because owning a home introduces expenses that don't disappear after closing.
Depending on the property, you may eventually encounter expenses involving:
-
HVAC systems
-
Plumbing
-
Appliances
-
Roof repairs
-
Electrical systems
-
Well or septic systems
-
Landscaping
-
Storm damage
-
Routine maintenance
Southern Maryland buyers should pay particular attention to the specific systems serving the property.
Some homes may use public water and sewer, while others may have private wells and septic systems. Waterfront, rural, older, condominium, and HOA properties can also introduce different ownership considerations.
Your home inspection and due diligence period can help you better understand the property you're considering.
How Much Should a First-Time Buyer Save?
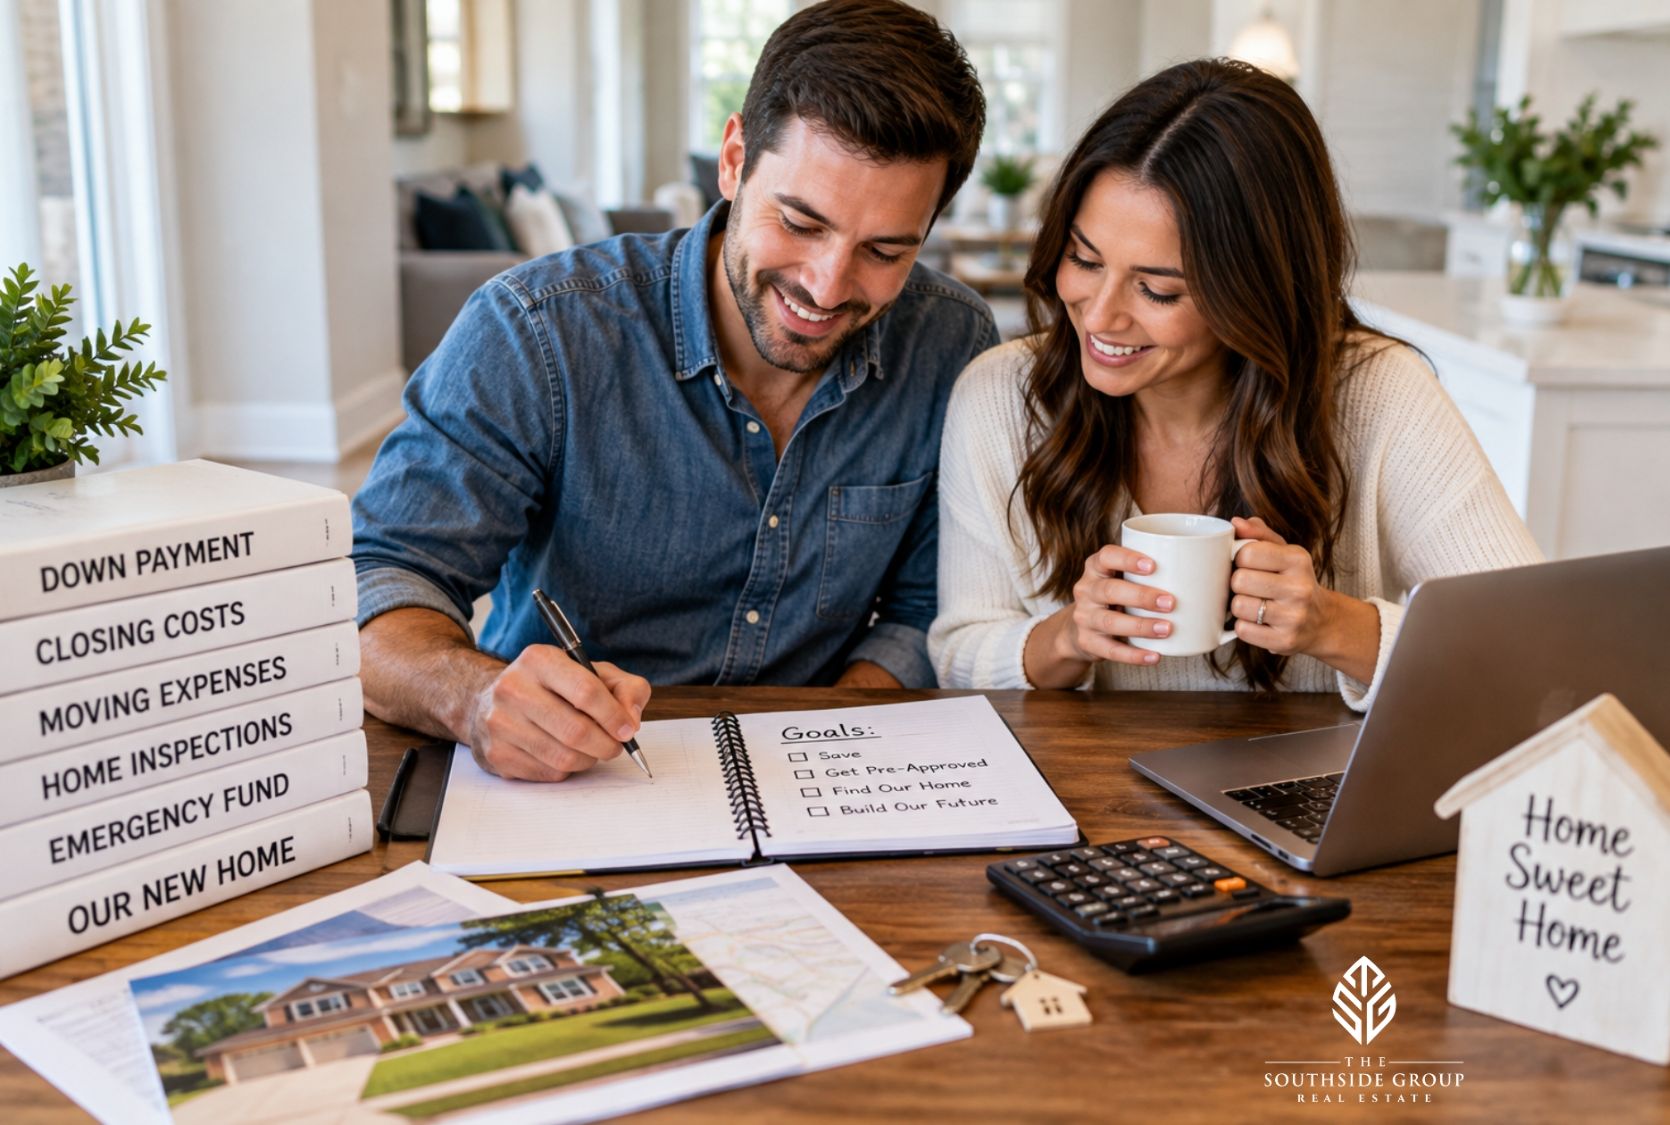
Instead of choosing an arbitrary number, first-time buyers can build a savings target with a simple framework:
Savings Target = Down Payment + Estimated Closing Costs + Other Upfront Expenses + Post-Closing Reserve
For example, if you're considering a $350,000 home and planning for a 5% down payment:
Down payment: $17,500
Then add estimated closing costs, transaction expenses, moving costs, and whatever emergency reserve you want to maintain.
That gives you a much more realistic target than simply saying:
"I need $17,500 to buy a $350,000 house."
You may need more—or potentially less cash out of pocket—depending on your financing, assistance programs, negotiated contract terms, and individual circumstances.
Maryland Down Payment Assistance May Change How Much You Need to Save
Before assuming that you need to accumulate your entire down payment and closing costs independently, investigate whether you qualify for assistance.
The Maryland Mortgage Program (MMP) offers mortgage products for eligible Maryland home buyers, and many of its loan products offer down payment assistance.
Options and eligibility vary.
Some programs are designed for first-time buyers, while others may be available to qualifying repeat buyers.
Instead of waiting until you've reached an arbitrary savings goal, consider speaking with an MMP-approved lender earlier in your planning process.
You may discover that your path to purchasing looks different from what you expected.
Should You Wait Until You Have 20% Saved?
Not necessarily.
Putting more money down can have advantages.
A larger down payment can reduce the amount you're borrowing, and depending on the financing, reaching certain down-payment thresholds may affect mortgage insurance, interest rates, or other loan costs.
But waiting until you reach 20% also has trade-offs.
If reaching 20% would require several additional years of saving, the homes available, home prices, mortgage rates, your income, and your personal circumstances could all change during that period.
There isn't one answer that works for every buyer.
Instead, compare scenarios.
Ask your lender what your estimated payment and cash-to-close requirements would look like with:
-
3% down
-
5% down
-
10% down
-
20% down
Then compare those numbers against your savings and monthly budget.
The objective isn't necessarily to make the largest down payment possible.
It's to choose a financing strategy that fits your overall financial situation.
Is Southern Maryland Expensive to Live In?
Whether Southern Maryland feels expensive depends on your income, household expenses, where you're moving from, the type of home you want, and where you choose to live.
Southern Maryland is also not one single housing market.
Housing options can vary considerably between St. Mary's County, Calvert County, and Charles County, as well as between individual communities within those counties.
A buyer looking for a home near Lexington Park or California may encounter a different mix of properties than someone searching in Leonardtown, Waldorf, La Plata, Prince Frederick, North Beach, or another Southern Maryland community.
That's why statewide home-price figures aren't enough to determine how much you should save.
Your savings target should be connected to the homes you're actually considering.
How Much Home Can You Afford in Southern Maryland?
Savings and affordability are related, but they aren't the same thing.
You could have enough cash to purchase a home while still choosing a price point that makes the monthly payment uncomfortable.
Before deciding how much to save, consider the full monthly cost of owning the home.
That can include:
-
Principal and interest
-
Property taxes
-
Homeowners insurance
-
Mortgage insurance, when applicable
-
HOA or condominium fees, when applicable
-
Utilities
-
Maintenance
-
Future repairs
This is where a lender's preapproval and your personal budget should work together.
A lender can help you understand the financing for which you may qualify.
Your household budget can help you determine what payment you actually want to carry.
For a deeper breakdown, read our guide to How Much Home Can You Afford in Southern Maryland?
A Better Way to Set Your Home-Buying Savings Goal
If buying a Southern Maryland home is your goal, work backward from the purchase instead of choosing a random savings number.
Step 1: Estimate Your Home Price Range
Start with a preliminary price range based on your income, debts, monthly budget, and general financing expectations.
Step 2: Talk to a Lender Early
You don't necessarily have to wait until you're ready to make an offer.
A conversation with a qualified mortgage professional can help you understand different financing options, approximate down-payment requirements, and potential obstacles you may want to address.
Step 3: Determine Your Down-Payment Strategy
Compare several possibilities rather than automatically choosing 20%.
Step 4: Estimate Closing and Upfront Costs
Account for expenses beyond the down payment.
Step 5: Protect Your Post-Closing Savings
Decide how much cash you want available after purchasing.
Step 6: Compare the Budget With Actual Southern Maryland Homes
Finally, see what your budget can realistically purchase in the communities you're considering.
That's where your financing plan becomes a real estate strategy.
How Much Should You Save Before Buying a Home in Southern Maryland?
There is no single dollar amount that every buyer should have saved.
For some buyers, a low-down-payment mortgage or eligible assistance program may reduce the amount they need upfront. Other buyers may decide that putting 10%, 20%, or more down better supports their financial goals.
The important thing is to account for more than the down payment.
Your home-buying savings plan should consider:
Down payment + closing costs + purchase-related expenses + moving costs + post-closing reserves.
Once you understand those numbers, you can determine whether you're ready to buy now or whether additional saving would put you in a stronger position.
Ready to See What Your Savings Could Buy in Southern Maryland?
You don't have to wait until you've reached an arbitrary savings number to start planning.
The Southside Group Real Estate helps buyers throughout St. Mary's County, Calvert County, and Charles County understand the local market and connect their budget with real homes that fit their goals.
Whether you're buying your first home, relocating to Southern Maryland, using VA financing, moving into a larger home, or simply trying to determine your next step, we can help you approach the process with a clearer plan.
Explore homes for sale in Southern Maryland or contact our team to start building your home-buying strategy.
Frequently Asked Questions
How much money do I need to buy a house in Maryland?
There is no universal amount. Your cash needs depend on the home's price, your mortgage program, down payment, closing costs, and other expenses. Some qualified buyers may have access to low- or no-down-payment financing or Maryland down payment assistance programs.
Is $20,000 a good amount of savings for buying a house?
$20,000 can be a meaningful home-buying fund, but whether it's enough depends on your price range and financing. Ask a lender to estimate your down payment, closing costs, and total cash to close before determining whether your savings are sufficient.
How much of a down payment do I need for a $300,000 house?
A 3% down payment is $9,000, 3.5% is $10,500, 5% is $15,000, 10% is $30,000, and 20% is $60,000. The amount actually required depends on your mortgage program and qualifications.
Do I need 20% down to buy a house in Maryland?
No. Some qualified buyers can purchase with substantially less than 20% down, and certain eligible VA and USDA borrowers may qualify for financing without a traditional down payment. Loan requirements vary.
How much should I save for closing costs?
The Consumer Financial Protection Bureau says closing costs typically range from approximately 2% to 5% of the purchase price, excluding the down payment. Your actual costs depend on your specific loan and transaction.
Should I use all my savings for a down payment?
Generally, buyers should consider the money they'll need for closing, moving, immediate expenses, and emergencies before deciding how much savings to apply toward a down payment. The CFPB suggests keeping an emergency cushion and describes three to six months of expenses as a useful rule of thumb.
Are there first-time home buyer programs in Maryland?
Yes. The Maryland Mortgage Program offers mortgage products and down payment assistance to eligible borrowers. Program availability and qualification requirements can change, so check current MMP information and speak with an approved lender.
FROM OUR BLOG
Charles County Events This Weekend | September 24–27, 2026
Charles County events this weekend offer plenty of ways to get out and explore Southern Maryland from September 24–27, 2026, with live entertainment, local shopping, family activities, creative workshops, community recreation, and more. If you’re searching for things to do near me in Charles County,
St. Mary’s County Events This Weekend | September 24–27, 2026
St. Mary’s County events this weekend bring four packed days of county-fair traditions, motorsports, art, live music, outdoor activities, fall fun, and community gatherings to Southern Maryland from September 24–27, 2026. If you’re searching for things to do near me in St. Mary’s County, there are p
Days on Market in St. Mary's, Calvert & Charles Counties
Days on Market in St. Mary's, Calvert & Charles Counties: What Sellers Should Expect Right Now If you're thinking about selling in Southern Maryland this fall, don't build your timeline around the neighbor who got an offer in four days. Some homes are still moving quickly. Others are sitting for six