Buying a home in Southern Maryland is an exciting opportunity, whether you're purchasing your first property, relocating for work, or looking for a home that better fits your lifestyle. With waterfront communities, established neighborhoods, rural properties, and convenient access to major employment centers, Southern Maryland offers a variety of housing options.
But finding the right home involves more than choosing a property you like.
From understanding the differences between St. Mary's, Calvert, and Charles counties to exploring mortgage options and navigating inspections, every decision can affect your homebuying experience.
This guide walks you through the process of buying a home in Southern Maryland, including how to prepare financially, compare communities, evaluate properties, and move confidently toward closing.
1. Understanding the Southern Maryland Housing Market
Southern Maryland includes three counties that offer different housing styles, geographic features, and commuting considerations.
St. Mary's County is closely connected to Naval Air Station Patuxent River and the surrounding defense and technology industries. Calvert County offers Chesapeake Bay communities, waterfront properties, and established residential areas. Charles County includes suburban neighborhoods, town centers, and more rural locations.
Across the region, buyers may encounter:
-
Single-family detached homes
-
Townhomes and condominiums
-
New construction communities
-
Established residential neighborhoods
-
Rural properties with larger lots
-
Waterfront and water-access homes
What affects home prices in Southern Maryland?
Several factors influence the value of an individual property, including its location, condition, size, features, and recent comparable sales.
For example, a property with direct waterfront access may have different maintenance and insurance considerations than an inland home. Similarly, new construction and older homes may involve different costs after purchase.
Rather than relying on a regional average, buyers should review recent comparable sales in the specific community where they want to purchase.
Local inventory and pricing conditions also change throughout the year. A home that was competitively priced several months ago may not reflect today's market.
The most useful approach is to compare active listings, pending sales when available, and recent closed transactions before deciding how much to offer.
2. Choosing Where to Buy in Southern Maryland
Location is one of the most important decisions in any home purchase.
Southern Maryland communities differ in housing options, proximity to employment centers, road access, shopping, and recreational opportunities.
St. Mary's County
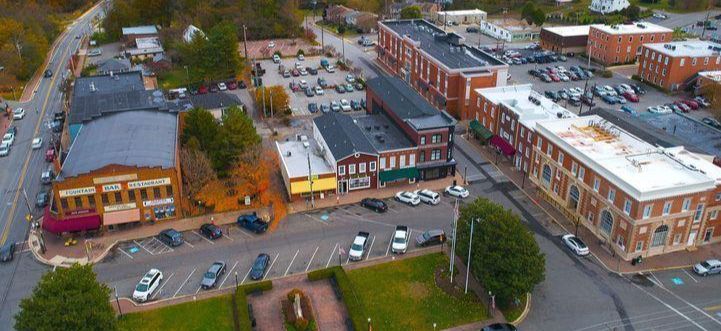
St. Mary's County offers a combination of historic communities, residential neighborhoods, and rural properties.
Communities to explore:
-
Lexington Park: Near NAS Patuxent River and local shopping
-
California: Residential communities and access to Route 235
-
Leonardtown: Historic downtown, restaurants, and local businesses
-
Hollywood: A mix of residential and rural properties
Buyers working near Patuxent River may want to compare actual travel routes during their normal commuting hours.
Calvert County
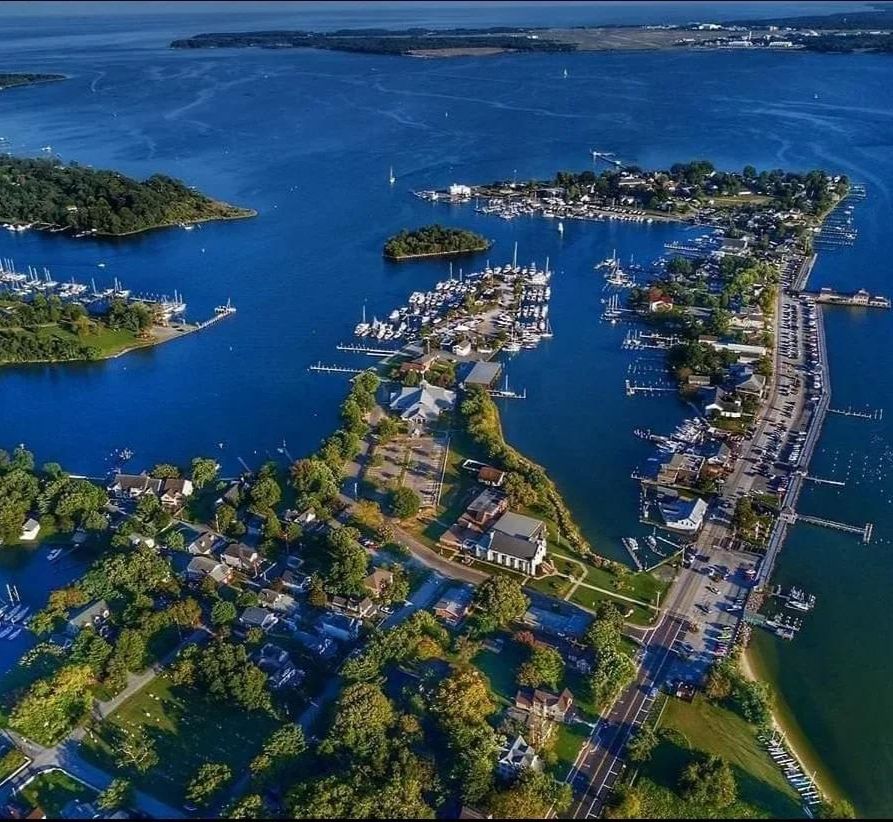 Calvert County stretches along the western shore of the Chesapeake Bay, offering a mix of inland residential areas and waterfront communities.
Communities to explore:
-
Prince Frederick: County services, shopping, and residential neighborhoods
-
Lusby: Established communities and access to waterfront recreation
-
Saint Leonard: Residential and rural properties
Buyers should pay particular attention to waterfront conditions, flood exposure, and property-specific access rights.
Charles County
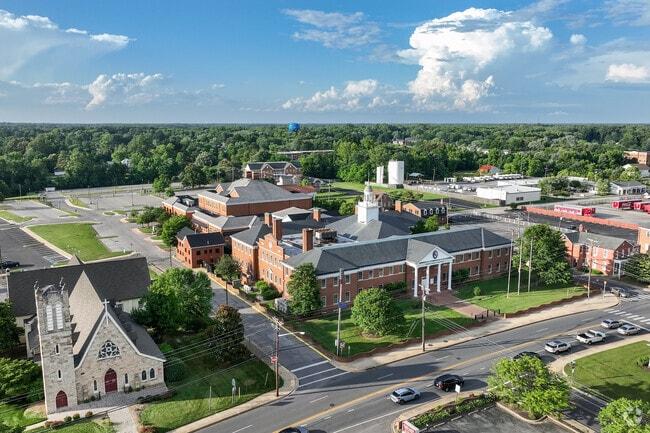 Charles County includes suburban developments, established towns, and rural areas, with road connections toward the Washington, D.C., metropolitan region.
Communities to explore:
-
Waldorf: Shopping, townhomes, and suburban residential developments
-
La Plata: A town center and surrounding residential communities
-
Indian Head: Residential areas near Naval Support Facility Indian Head
When comparing locations, consider Route 301, Route 5, and other daily travel corridors rather than relying solely on mileage.
How to narrow your location search
Before choosing a community, identify the features that matter most to your daily routine.
Consider travel time to work, access to shopping and medical services, outdoor recreation, property maintenance, and the type of home you want.
Visiting a community at different times can also help you understand traffic patterns and nearby activity.
3. How Much House Can You Afford in Southern Maryland?
Before scheduling home tours, determine a comfortable monthly housing budget.
A lender's maximum pre-approval amount is not necessarily the amount you should spend.
Your budget should account for the full cost of homeownership, including:
-
Mortgage principal and interest
-
Property taxes
-
Homeowners insurance
-
Mortgage insurance, when applicable
-
HOA or condominium fees
-
Utilities and routine maintenance
-
Repairs and emergency savings
Down payments and closing costs
The amount you need upfront depends on your mortgage program, credit profile, and property.
Some financing programs offer low-down-payment options, while eligible VA borrowers may qualify for financing without a down payment.
However, a low down payment does not mean buying a home is free of upfront expenses.
Buyers may still need funds for inspections, appraisal-related costs, earnest money, closing expenses, and moving.
Ask your lender for a written estimate that includes both your expected monthly payment and the cash needed to close.
Why property taxes deserve attention
Property tax obligations can vary based on location, assessed value, applicable rates, and available credits.
Maryland's Department of Assessments and Taxation maintains property assessment records, but an assessed value should not be treated as the same thing as a current market appraisal.
You can review Maryland's official property information search instructions when researching a home.
For an accurate estimate of future taxes, consult the appropriate county or municipality and your settlement or lending professional.
4. Mortgage Options and First-Time Buyer Programs
Southern Maryland buyers have access to several mortgage options, each with different eligibility requirements and financial considerations.
Conventional loans
Conventional mortgages are commonly offered through banks, credit unions, and mortgage lenders.
Depending on the loan product and borrower qualifications, some conventional loans allow down payments below 20%.
Mortgage insurance may apply when the down payment is below the applicable threshold.
FHA loans
Federal Housing Administration-insured mortgages can provide an alternative for qualified buyers who may not meet certain conventional loan requirements.
These loans have specific credit, down payment, property, and mortgage insurance requirements.
VA loans
Eligible service members, veterans, and certain surviving spouses may qualify for VA-backed home financing.
Potential benefits include no VA-required down payment in qualifying circumstances and no monthly private mortgage insurance.
A Certificate of Eligibility establishes eligibility for the VA home loan benefit, but the borrower must still meet lender requirements. Some borrowers also pay a VA funding fee.
The U.S. Department of Veterans Affairs purchase loan guide explains the program and application process.
USDA loans
USDA-backed mortgages may be available for eligible properties in qualifying rural areas.
Eligibility depends on the property's location, household income, lender requirements, and other program rules.
Not every property with a rural appearance qualifies.
Maryland Mortgage Program
The Maryland Mortgage Program provides eligible buyers with mortgage products and certain down payment or closing cost assistance options.
Its offerings include first-time buyer products, Flex loans, and specialty programs. Availability and terms depend on current program rules and borrower qualifications.
Review the Maryland Mortgage Program's official home loan options and speak with an approved lender about eligibility.
For buyers beginning the financing process, our mortgage pre-approval resources provide a useful starting point.
5. The Step-by-Step Homebuying Process in Southern Maryland
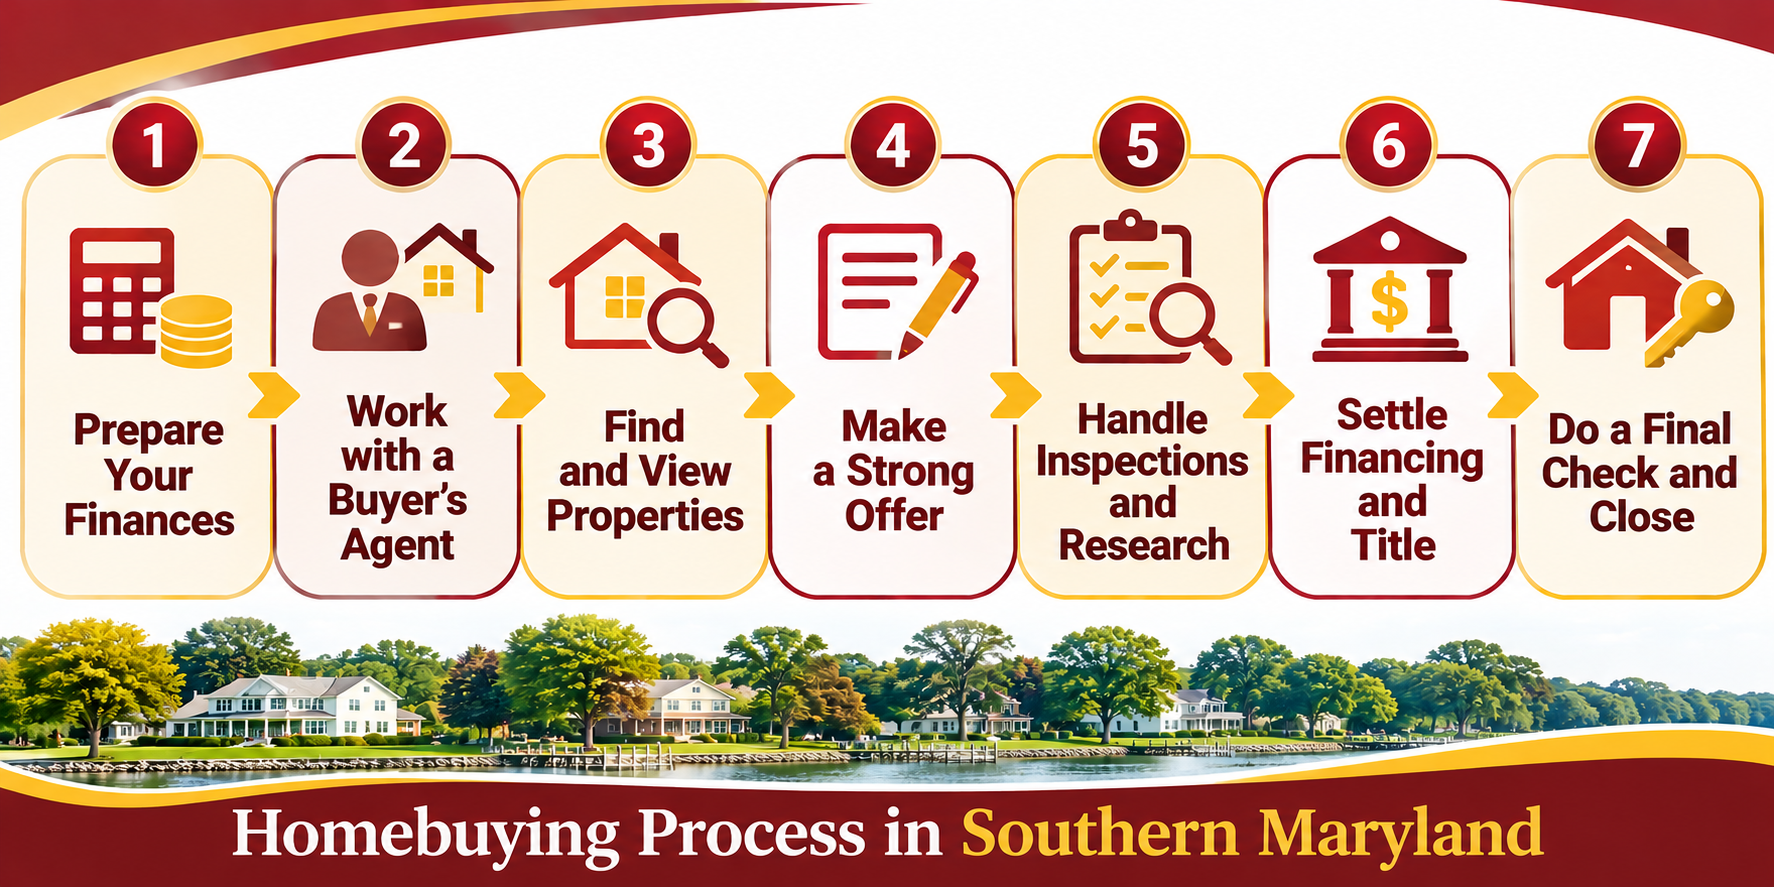
Understanding the sequence of a real estate transaction can help you make informed decisions and avoid unnecessary delays.
-
Get financially prepared
Review your credit, savings, income, and existing debts. Compare mortgage options and obtain lender pre-approval before making offers.
-
Choose a buyer's real estate agent
Discuss your goals, property preferences, and representation agreement. In Maryland, a written buyer agency agreement is required before an agent provides brokerage services on your behalf. Review the services, compensation, and agreement terms before signing.
-
Search and tour homes
Compare homes against your priorities, including layout, condition, location, and total ownership costs. Review disclosures and available property documents.
-
Submit an informed offer
Your offer may address purchase price, financing, deposit, settlement timing, contingencies, and other negotiated terms. Comparable sales help provide pricing context.
-
Complete inspections and due diligence
Arrange appropriate professional inspections within the deadlines established by your contract. Evaluate findings and any available contractual options before proceeding.
-
Finalize financing and title work
The lender evaluates the loan, may order an appraisal, and completes underwriting. The settlement process includes title review and preparation of closing documents.
-
Complete the final walkthrough and closing
Confirm the property's condition, review your closing figures, and follow verified settlement instructions. Ownership transfers according to the completed transaction documents and applicable procedures.
The exact timeline varies by contract, financing, property condition, and the parties involved.
A well-organized purchase begins with understanding your deadlines rather than assuming every transaction follows the same schedule.
6. Important Property Considerations in Southern Maryland
Some Southern Maryland homes have features that require additional research beyond a standard interior inspection.
Private wells and septic systems
Properties outside public water and sewer service areas may rely on private wells or septic systems.
Before purchasing, investigate the age, condition, maintenance history, permits, and available inspection results for these systems.
A general home inspection may not provide the specialized testing needed to evaluate a well or septic system.
The Environmental Protection Agency offers a homebuyer's guide to septic systems, including inspection and maintenance considerations.
Waterfront homes and flood exposure
Waterfront and water-access properties can involve additional ownership considerations.
Before making a final decision, investigate:
-
Flood zone designation and potential insurance requirements
-
Shoreline condition and erosion concerns
-
Waterfront access rights and easements
-
Dock, pier, or shoreline improvement permits
-
Property boundaries and maintenance responsibilities
Waterfront proximity alone does not establish whether a home is in a regulated flood zone.
Check the property using official flood mapping and obtain property-specific insurance quotes.
HOA and condominium requirements
If a property belongs to a homeowners association or condominium, review the governing documents and financial obligations.
Pay attention to monthly or annual fees, maintenance responsibilities, architectural restrictions, special assessments, and any available association financial information.
Property records and permits
For older homes, additions, finished basements, or significant renovations, verify available permits and records through the appropriate local authorities.
Public property records can be useful, but they do not replace professional inspections, a survey when appropriate, or title examination.
7. Buying a Home During a Military PCS Move
Military relocation is an important part of Southern Maryland's real estate landscape, particularly around Naval Air Station Patuxent River.
A permanent change of station can introduce additional timing and logistical challenges when buying a home.
If you're moving to the region, start by identifying your expected reporting timeline, financing requirements, and housing priorities.
Compare communities based on your actual assignment
Buyers assigned near NAS Patuxent River often investigate communities in St. Mary's County, as well as selected locations in neighboring Calvert County.
However, the most practical location depends on your assigned worksite, expected schedule, transportation needs, and personal housing preferences.
Test commuting routes using realistic travel times before narrowing your search.
Prepare for remote home shopping
When an in-person visit is difficult, request detailed property information and live video tours.
Ask about exterior conditions, surrounding roads, potential maintenance concerns, and features that may not be obvious in listing photographs.
Remote tours are useful, but they should not replace appropriate professional inspections and independent property research.
Coordinate financing with PCS timing
If you plan to use VA financing, discuss your eligibility, occupancy requirements, and purchase timeline with a lender familiar with the program.
Military orders do not automatically guarantee mortgage approval or a particular closing date.
Planning early gives you more time to evaluate options without making a rushed purchase.
8. Common Homebuying Mistakes and How to Avoid Them
Even experienced buyers can overlook important details during a real estate transaction.
Here are several issues worth watching:
- Shopping before understanding your budget. A home search becomes more productive when you know your financing options and comfortable monthly payment.
- Focusing only on the listing price. Taxes, insurance, utilities, maintenance, and association fees can materially affect affordability.
- Skipping specialized inspections. A property with a private well, septic system, or waterfront improvements may require additional professional evaluation.
- Making major financial changes before closing. New debt, employment changes, or large unexplained deposits can create underwriting questions. Discuss significant changes with your lender.
- Overlooking contract deadlines. Inspection, financing, deposit, and settlement deadlines may affect your rights and obligations.
- Assuming every Southern Maryland community is interchangeable. Property types, road access, utilities, and daily travel patterns can differ considerably, even within the same county.
Frequently Asked Questions
Is Southern Maryland a good place to buy a home?
Southern Maryland offers a variety of housing types, including suburban neighborhoods, rural properties, townhomes, and waterfront residences. Whether a particular location is a good fit depends on your budget, transportation needs, property preferences, and long-term plans.
How much money do I need to buy a house in Southern Maryland?
The amount depends on the purchase price, loan program, down payment, closing costs, and other expenses. Some qualified buyers may be eligible for low-down-payment or no-down-payment financing. A lender can prepare a personalized estimate.
Can I buy a home in Southern Maryland with a VA loan?
Yes, eligible borrowers can use VA-backed financing to purchase qualifying homes in Southern Maryland. Approval depends on eligibility, lender underwriting, property requirements, and other program conditions.
Do I need a home inspection when buying a house in Maryland?
A home inspection is strongly recommended, although the contractual requirement depends on the transaction. Specialized inspections may be appropriate for septic systems, wells, waterfront structures, or other property features. Review inspection rights and deadlines before signing an agreement.
How long does it take to buy a home in Southern Maryland?
The timeline depends on financing, the property, negotiations, inspections, title work, and the agreed settlement date. A lender and real estate agent can help establish a realistic schedule for your specific transaction.
A thoughtful homebuying strategy balances the condition of the property, your financial comfort, and your longer-term plans.
The right purchase is not simply the home with the most appealing photographs. It's a property you understand, can reasonably afford, and have evaluated with the appropriate information.
Ready to Start Your Southern Maryland Home Search?
Buying a home is a major decision, and understanding the local market can make the process easier.
Whether you're exploring St. Mary's County, comparing communities in Calvert County, or considering a move to Charles County, The Southside Group Real Estate can help you navigate the local homebuying process.
Start by exploring Southern Maryland homes for sale and identifying properties that match your priorities.
When you're ready to discuss your options, Billy Rabbitt and The Southside Group Real Estate are available to help you plan your next steps.
FROM OUR BLOG
Black Friday Home Upgrades for Southern Maryland Sellers
Black Friday is usually associated with holiday shopping, but it can also be an opportunity for homeowners planning to sell their properties. From fresh paint and updated lighting to cleaning equipment and storage solutions, seasonal home improvement deals can help sellers purchase practical supplie
How Much Is My Home Worth in Southern Maryland?
If you've been thinking about selling your house, refinancing, or simply checking how much equity you've built, you've probably asked yourself: "How much is my home worth?" Understanding your Southern Maryland home value starts with knowing what buyers are willing to pay for a property like yours in
Long Beach & Calvert Beach Real Estate Market Update – November 20, 2026
The real estate market in Long Beach and Calvert Beach continues to offer opportunities for buyers looking along this stretch of Southern Maryland's Chesapeake Bay shoreline. This week, Long Beach has a wider selection of available homes and several vacant lots on the market, while Calvert Beach has