 Buying your first home can feel more achievable once you understand the financing and assistance programs available to you. For buyers in St. Mary’s, Calvert, and Charles counties, several Southern Maryland first-time home buyer programs may help with down payments, closing costs, student loan debt, or other barriers to buying a home.
The important part is understanding what each program actually provides. Some programs people call “grants” are really deferred loans that may eventually need to be repaid. Eligibility can also depend on income, credit, purchase price, occupation, location, and the type of mortgage you use.
Here is what Southern Maryland buyers should know in 2026.
What Grants Are Available for First-Time Homebuyers in Maryland?
Maryland offers several programs to help eligible first-time homebuyers manage the upfront costs of purchasing a home. Through the Maryland Mortgage Program (MMP), qualified buyers may access competitive mortgage interest rates and down payment or closing cost assistance.
However, not all homebuyer assistance is free grant money. Many Maryland Mortgage Program options provide assistance through a 0% interest, deferred second mortgage. These loans generally do not require monthly payments, but the assistance must be repaid when the first mortgage ends, such as when the home is sold, refinanced, transferred, or the mortgage is paid off.
Who Qualifies for Maryland's 1st Time Advantage Program?
The MMP 1st Time Advantage program is designed for eligible first-time homebuyers and offers some of the program's most competitive 30-year fixed mortgage interest rates.
You may qualify if you are purchasing your first home or meet one of the following exceptions:
-
You have not owned a principal residence in more than three years.
-
You are purchasing a home in an eligible targeted area and will sell your current home before closing.
-
You are an honorably discharged veteran who meets the program's first-time homebuyer exemption requirements and provides the required documentation.
Income limits, purchase price limits, credit requirements, and other eligibility criteria may apply. The Maryland HomeCredit Program cannot be combined with the 1st Time Advantage product line.
Maryland 1st Time Advantage Loan and Assistance Options
|
Program |
Available assistance |
|---|---|
|
1st Time Advantage Direct |
No MMP down payment assistance, but generally offers highly competitive interest rates. Eligible external assistance may be used. |
|
1st Time Advantage 6000 |
$6,000 toward down payment and closing costs through a 0% deferred second mortgage. |
|
1st Time Advantage 3% Loan |
Down payment assistance equal to 3% of the first mortgage through a 0% deferred second loan. |
|
1st Time Advantage 4% Loan |
Assistance equal to 4% of the first mortgage through a 0% deferred second loan. |
|
1st Time Advantage 5% Loan |
Assistance equal to 5% of the first mortgage through a 0% deferred second loan. |
|
HomeStart |
For eligible borrowers earning no more than 50% of area median income (AMI), assistance equal to 6% of the first mortgage through a 0% interest, 30-year deferred loan. |
|
MMP-UPLIFT |
Assistance equal to 5% of the first mortgage when purchasing an eligible UPLIFT property. |
|
First Homes for First Responders and Teachers |
Assistance equal to 5% of the first mortgage through a 0% deferred second loan for eligible first-time buyers working in qualifying professions. |
Additional Assistance Through Maryland's Partner Match Program
Maryland also offers a Partner Match Program for eligible buyers receiving qualifying financial assistance from an approved employer, builder, or community partner.
Buyers using the 1st Time Advantage 6000 product may qualify for additional matching assistance when program requirements are met.
What Should Southern Maryland Homebuyers Know?
If you're buying your first home in St. Mary's County, Calvert County, or Charles County, Maryland's down payment assistance programs may help reduce the amount of money you need upfront.
However, the best option depends on your household income, financing qualifications, purchase price, property eligibility, and long-term financial goals.
Before choosing a program, speak with an MMP-approved lender to understand the current interest rates, assistance amounts, repayment requirements, and whether different assistance programs can be combined.
Official resources:
Program availability, funding, mortgage rates, eligibility requirements, and assistance terms are subject to change. Always confirm current details with the Maryland Mortgage Program and an approved lender before making financial decisions.
How Does the Maryland Mortgage Program Help First-Time Buyers?
The Maryland Mortgage Program is administered through the Maryland Department of Housing and Community Development. Its 1st Time Advantage products combine a 30-year fixed-rate first mortgage with different assistance choices for eligible buyers.
For MMP purposes, being a first-time buyer does not necessarily mean you have never owned a home.
A buyer may meet the first-time requirement if it has been more than three years since they owned a principal residence. Maryland also provides specific exceptions for certain buyers, including qualifying veterans and purchases in designated targeted areas.
That distinction matters in Southern Maryland because Calvert, Charles, and St. Mary’s counties are currently listed by MMP as non-targeted counties. Buyers purchasing in these counties generally cannot rely on the targeted-area exception to the first-time-buyer requirement.
Down Payment and Closing Cost Assistance
One of the biggest advantages of MMP is that eligible buyers can choose products that provide money toward their upfront purchase expenses.
But the amount of assistance should not be considered in isolation.
Different MMP products can have different mortgage rates and qualification requirements. A buyer should compare the entire financing package, including the first mortgage, second loan, monthly payment, cash required at closing, and circumstances that trigger repayment.
Before searching for homes, consider completing the required education and discussing mortgage pre-approval with an appropriate lender so you understand which options actually fit your finances.
What Are the MMP Income Limits for 2026?
The Maryland Mortgage Program has income and purchase-price limits, and those limits are updated periodically.
Maryland issued new MMP income and purchase-price limits effective for loans reserved on or after June 24, 2026. The state noted that most county income limits increased.
Rather than relying on an older chart found in a blog or social media post, check the current MMP limits for the county where you plan to buy. Household income limits can vary by location and household size, while the applicable mortgage product can have additional requirements.
The same principle applies to purchase-price and mortgage limits.
If you are considering a home in St. Mary’s, Calvert, or Charles County, have an MMP-approved lender confirm the current limits for your specific situation before assuming you qualify.
First-Time Home Buyer Programs in St. Mary’s, Calvert, and Charles Counties
Statewide Maryland programs can be relevant throughout Southern Maryland, but local assistance is not identical from county to county.
St. Mary’s County First-Time Home Buyers
Eligible buyers purchasing in St. Mary’s County can investigate statewide Maryland Mortgage Program options, including 1st Time Advantage and applicable specialty programs.
For buyers relocating to the area for NAS Patuxent River or purchasing their first home after a PCS move, VA financing may also deserve consideration when the buyer is eligible.
First-time buyers can explore communities such as Lexington Park, California, and Leonardtown based on their budget, property needs, location preferences, and financing requirements.
Calvert County First-Time Home Buyers
Calvert County buyers can also investigate statewide MMP financing and down payment assistance.
Calvert County currently identifies House Keys 4 Employees among its community resources. Because employer-based assistance has its own eligibility requirements, buyers should verify whether their employer participates and whether assistance can be combined with their intended mortgage.
Buyers comparing communities can also research homes in areas such as Prince Frederick and Lusby.
Charles County First-Time Home Buyers
Charles County has an additional local program worth checking.
The county's Settlement Expense Loan Program, or SELP, currently provides up to $6,000 in settlement-expense assistance to qualified low- and moderate-income first-time homebuyers. The assistance is secured by a second mortgage, with repayment deferred until circumstances such as resale, transfer, refinancing, or discontinuing the property as the buyer's principal residence.
Buyers should confirm current funding and eligibility directly with Charles County before depending on SELP assistance.
Those considering Charles County can also research communities such as La Plata and Waldorf.
What Credit Score Do I Need to Buy a $250,000 House?
There is no single minimum credit score required to purchase a $250,000 home in Maryland. Your ability to qualify for a mortgage depends on several factors, including your loan program, lender requirements, income, existing debts, down payment, credit history, and overall financial situation.
Different mortgage programs have different credit score requirements.
For example, the Maryland Mortgage Program (MMP) offers home loan and down payment assistance options with credit score requirements that vary by product. Programs such as 1st Time Advantage and Maryland SmartBuy may have different eligibility standards, so it's important to review the latest program guidelines with an approved lender.
VA home loans work differently. The U.S. Department of Veterans Affairs does not establish a universal minimum credit score for its VA loan guaranty program. However, individual mortgage lenders may set their own credit requirements and underwriting standards.
Rather than focusing only on the question, "What credit score do I need to buy a $250,000 house?", consider asking:
"Which mortgage programs could I qualify for, and how much house can I comfortably afford?"
A mortgage lender can evaluate your credit profile, income, debt-to-income ratio, available savings, and financing options to help determine your eligibility and estimated monthly mortgage payment.
For first-time homebuyers in Southern Maryland, including St. Mary's County, Calvert County, and Charles County, exploring conventional loans, FHA loans, VA loans, and Maryland Mortgage Program options can be an important step toward finding the right financing solution.
Helpful resources:
Mortgage eligibility, credit score requirements, and loan terms vary by lender and program and are subject to change. Consult a qualified mortgage professional for guidance based on your financial circumstances.
Is $20,000 Enough for a Down Payment on a House?
It can be, depending on the home price, mortgage program, closing costs, and other expenses.
Consider the basic math:
-
$20,000 is 8% of a $250,000 purchase price.
-
$20,000 is about 6.7% of a $300,000 purchase price.
-
$20,000 is 5% of a $400,000 purchase price.
But a down payment is only one part of the money you may need to purchase a home.
Depending on your transaction, you may also need funds for closing costs, inspections, prepaid expenses, moving expenses, reserves, and other costs. The exact amount varies.
This is where down payment or closing-cost assistance can potentially change the calculation. Instead of assuming you need a particular percentage saved, talk with a lender about the mortgage programs for which you may qualify and the estimated cash required to close.
What If I Have Student Loans?
If you’re a first-time homebuyer in Maryland with outstanding student loan debt, the Maryland SmartBuy Home Loan Program may help you become a homeowner while managing your student loans.
Through Maryland SmartBuy, eligible homebuyers can receive assistance toward qualifying student loan debt, with the amount based on a percentage of the home’s purchase price and subject to the program’s maximum assistance limit. This benefit can help reduce student debt while making homeownership more accessible.
To qualify, at least one borrower must have eligible student loan debt that can be paid off at closing. If the outstanding balance exceeds the available assistance, the borrower is responsible for covering the remaining amount.
The student loan assistance is structured as a zero-interest loan that may be fully forgiven after the required holding period, provided all program conditions are met. Additional eligibility requirements apply, including minimum credit score standards, Maryland Mortgage Program (MMP) income and home purchase price limits, occupancy of the property as a primary residence, and financing through an approved SmartBuy lender.
Before applying, review the current Maryland SmartBuy program guidelines to confirm the available student debt assistance, loan forgiveness terms, and eligibility requirements. Working with an approved lender can help you determine whether this Maryland first-time homebuyer program fits your financial situation and homeownership goals.
Can VA Loans Help First-Time Buyers in Southern Maryland?
 For eligible service members and veterans, a VA-backed purchase loan may be particularly relevant in Southern Maryland because of the military community surrounding NAS Patuxent River.
A VA loan is not a first-time homebuyer grant. It is a federal home loan benefit available to eligible borrowers.
The Department of Veterans Affairs says an eligible borrower may use a VA-backed purchase loan to buy a first home. VA-backed loans can often be made without a down payment when program requirements are met and the sales price does not exceed the appraised value.
VA itself does not establish a universal minimum credit score, but lenders can impose their own standards. Borrowers also need to meet applicable VA and lender requirements for credit, income, occupancy, and eligibility and obtain the appropriate Certificate of Eligibility.
For a military buyer making a PCS move to Southern Maryland, it can be useful to evaluate VA financing alongside any Maryland programs for which the buyer may qualify rather than assuming one option is automatically best.
Is 2026 a Good Year for First-Time Home Buyers?
There is no universal answer.
A good time to buy is not determined by the calendar alone. It depends on your finances, expected length of ownership, available homes, mortgage options, monthly payment, cash reserves, and personal plans.
Interest rates and Southern Maryland housing conditions can also change during the year. A market that works for one buyer may not work for another.
For that reason, first-time buyers should be cautious about waiting for a supposedly “perfect” market or rushing because of a prediction.
A better approach is to determine:
-
What monthly housing payment fits your budget?
-
How much cash can you comfortably use without draining emergency savings?
-
Which mortgage and assistance programs are actually available to you?
-
How long do you expect to own the property?
-
Are suitable homes available within your approved price range?
If those pieces align, buying may make sense even when market conditions are not perfect.
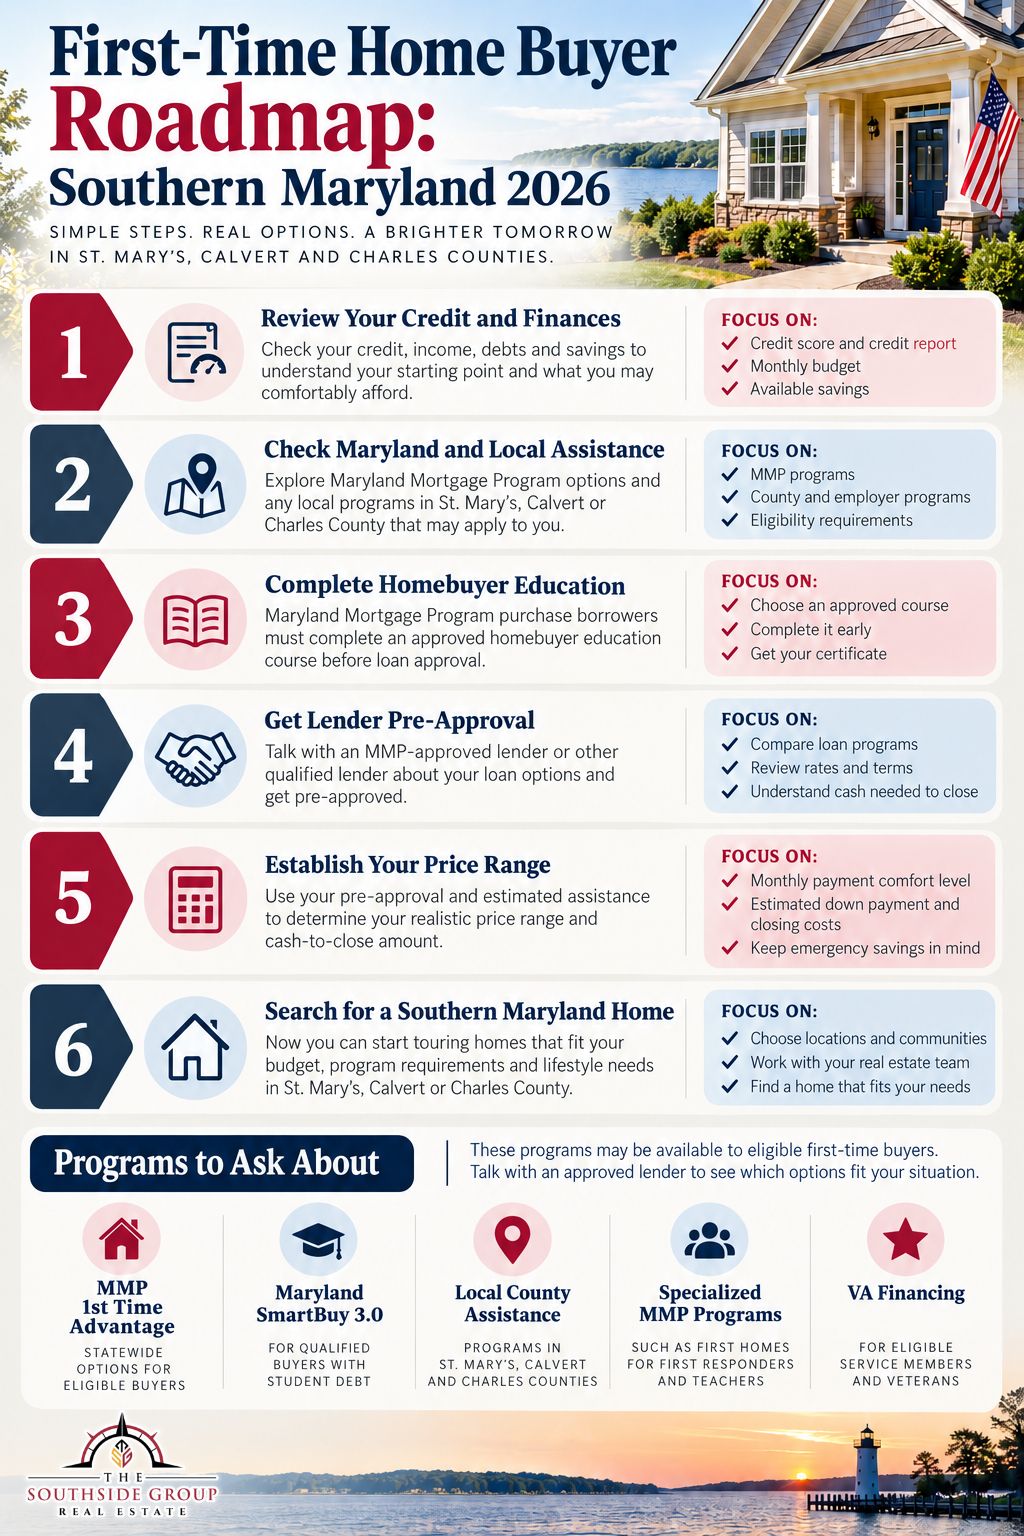
How to Get Started as a First-Time Buyer in Southern Maryland
Before spending weekends touring houses, get the financial side organized.
Start by reviewing your credit, income, debts, savings, and expected monthly budget. Then investigate Maryland and local assistance programs that could apply to your situation.
Maryland Mortgage Program purchase borrowers must complete approved homebuyer education before loan approval. The completion certificate must be issued within 12 months before settlement. Maryland encourages buyers to complete the course early because housing counselors can also help identify potential sources of assistance.
Next, speak with an appropriate lender about pre-approval and ask specifically about MMP, FHA, conventional, VA, or other financing options that may apply to you.
Once you know your realistic price range and estimated cash needed to close, you can browse available Southern Maryland homes with a clearer understanding of what fits your budget.
First-time homebuyer programs can make buying more accessible for some Maryland buyers, but the right program depends on your individual circumstances. Program limits, funding, rates, and eligibility can change, so verify current requirements before making financial decisions.
Frequently Asked Questions About First-Time Home Buyer Programs in Southern Maryland
Do I have to be a first-time buyer to use the Maryland Mortgage Program?
Not always. MMP Flex loans are available to first-time and repeat buyers who meet applicable requirements. The 1st Time Advantage line generally requires first-time-buyer status or a qualifying exception. Maryland Mortgage Program
Can I combine Maryland down payment assistance with other assistance?
Sometimes. Maryland's Partner Match program can provide qualifying buyers using 1st Time Advantage 6000 or Flex 6000 with matching assistance of up to $2,500 when eligible assistance comes from an approved partner. Other combinations depend on the programs involved and applicable lender and investor rules. Maryland Mortgage Program
Do Maryland first-time home buyers have to take a class?
For MMP purchase loans, borrowers must complete approved homebuyer education before approval, and the certificate must have been issued within 12 months before settlement. Other funding sources can impose additional requirements. Maryland Mortgage Program
Can I qualify for Maryland homebuyer assistance if I have student loans?
Yes, you may qualify for Maryland homebuyer assistance even if you have student loan debt.
The Maryland SmartBuy 3.0 Program is designed to help eligible homebuyers purchase a home while addressing qualifying student loan debt. Depending on current program guidelines, eligible buyers may receive assistance toward student loan repayment, subject to program limits and eligibility requirements.
Learn more about available benefits and qualifications through the Maryland Mortgage Program.
Ready to Buy Your First Home in Southern Maryland?
Buying your first home starts with understanding your budget, exploring mortgage and down payment assistance programs, and finding the right property.
Whether you're searching in St. Mary's County, Calvert County, or Charles County, The Southside Group Real Estate can guide you through the local homebuying process.
Explore our first-time homebuyer resources or contact our Southern Maryland real estate team to start your home search with confidence.
FROM OUR BLOG
Calvert County Community Events | October 15–18, 2026
Calvert County events this weekend are bringing plenty of fall fun, outdoor adventures, and community celebrations to Southern Maryland! Whether you're looking for pumpkin patches, family-friendly festivals, spooky ghost tours, or local gatherings, there's something worth adding to your calendar. If
Charles County Community Events | October 15–18, 2026
Charles County MD events this weekend bring an exciting mix of fall festivals, family-friendly entertainment, community celebrations, and outdoor adventures to Southern Maryland from October 15–18, 2026. Whether you're searching for things to do near Waldorf, planning a Saturday outing in La Plata,
St. Mary's County Community Events | October 15–18, 2026
St. Mary's County events this weekend are bringing together the best of Southern Maryland's fall season, with oyster festivals, pumpkin patches, farm adventures, live music, theater performances, vintage shopping, and community celebrations happening October 15–18, 2026! Whether you're searching for