First-time home buyer Maryland rules may be more flexible than you think. You do not necessarily have to be buying your first house ever to qualify as a first-time homebuyer under certain Maryland programs.
For the Maryland Mortgage Program (MMP), Maryland currently defines a first-time homebuyer as someone who has not owned residential property for three years or more. That means someone who owned a home in the past, sold it, and has been out of homeownership for at least three years may potentially qualify as a first-time buyer again.
Here is what Maryland buyers should know about the three-year rule, exceptions, financing programs, credit, income, and preparing to buy a home in 2026.
What Qualifies as a First-Time Home Buyer in Maryland?
The phrase “first-time homebuyer” sounds straightforward, but it does not always mean someone who has never owned real estate.
Under the current Maryland Mortgage Program eligibility guidelines, someone who has not owned residential property for three years or more is considered a first-time homebuyer for MMP purposes. Maryland also specifically notes that this MMP definition is not necessarily the same definition used for recording-tax purposes.
Understanding Maryland's Three-Year Rule
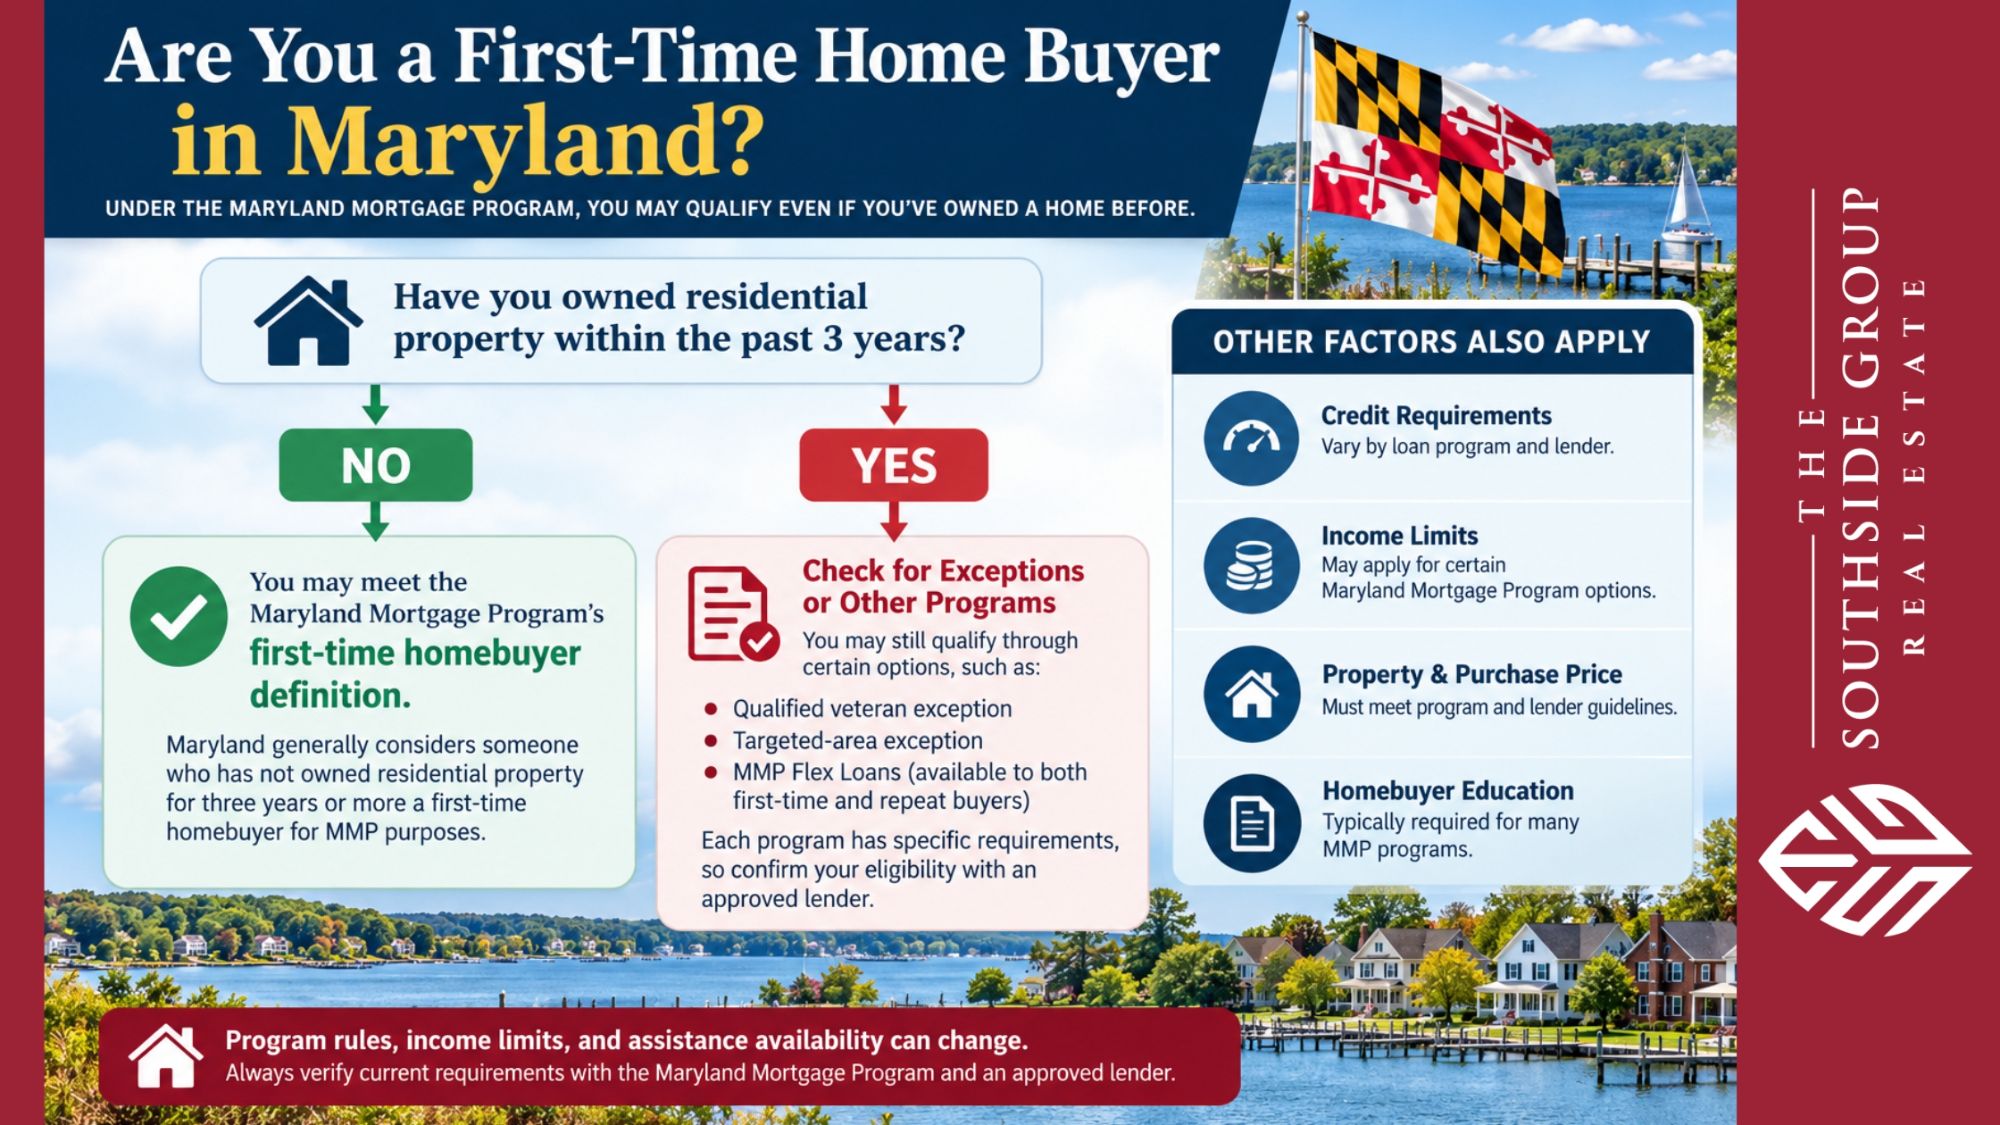
Suppose you previously owned a home but sold it several years ago. If you have now gone at least three years without owning residential property, you may meet MMP's first-time-homebuyer definition.
In other words, the important question may not be:
“Have I ever owned a home?”
Instead, for MMP eligibility, the question becomes:
“Have I owned residential property during the last three years?”
This is why former homeowners should not automatically assume that they are ineligible for first-time buyer programs.
Am I Still Considered a First-Time Home Buyer?
Potentially, yes.
A person who owned a home years ago but has not owned residential property for three years or more can potentially meet Maryland Mortgage Program's first-time-homebuyer definition.
However, meeting the first-time-buyer definition is only one part of qualifying. Individual MMP products can also have household-income limits, credit requirements, purchase-price limits, homebuyer-education requirements, lender underwriting requirements, and other conditions.
Because circumstances differ, buyers should verify eligibility with a state-approved mortgage lender before making financial decisions.
Can You Qualify If You've Owned a Home Before?
Yes, depending on the program and your circumstances.
The three-year rule is one of the most important examples. But Maryland also identifies additional situations where someone who does not meet the standard first-time-homebuyer requirement may have options.
Exceptions to Maryland's First-Time Buyer Requirement
Maryland identifies an exception for certain veterans using their first-time-homebuyer exemption for the first time. Maryland also allows repeat buyers to use any MMP loan product when purchasing in a designated Targeted Area and meeting the applicable requirements.
A Targeted Area is a geographic area established under federal criteria. Maryland notes that income limits may be higher in these areas and that the standard first-time-buyer requirement can be waived. However, buyers should verify the specific property rather than assuming that an entire community qualifies.
Repeat buyers may also have access to MMP Flex Loans. Maryland currently describes Flex products as 30-year fixed-rate loans available to both first-time and repeat homebuyers. Certain Flex options include deferred, zero-interest down payment assistance.
What First-Time Home Buyer Programs Are Available in Maryland?
The Maryland Mortgage Program is administered through the Maryland Department of Housing and Community Development and offers multiple financing options.
One important category is MMP 1st Time Advantage.
Maryland Mortgage Program and 1st Time Advantage
Current 1st Time Advantage offerings include several options that may provide assistance with down payment and closing costs.
For example, Maryland currently lists a 1st Time Advantage 5% Loan, which provides eligible borrowers with down payment assistance equal to 5% of the first mortgage through a zero-percent deferred second lien. Maryland also lists HomeStart, MMP-UPLIFT, and a program for eligible first responders and teachers, each with its own requirements.
These programs are not automatic grants for everyone who identifies as a first-time buyer. Depending on the program, borrowers may need to complete approved homebuyer education and meet applicable income, credit, purchase-price, lender, insurer, and other eligibility requirements.
Maryland also announced updated 2026 income and purchase-price limits, effective for MMP loans reserved on or after June 24, 2026. Because these limits can change annually, buyers should check current figures rather than relying on numbers from an older article or social media post.
For more information about preparing financially for a purchase, explore our Mortgage & Financing Tips.
First-Time Home Buyer Assistance in Southern Maryland
Buyers in St. Mary's, Charles, and Calvert counties can potentially use qualifying statewide Maryland programs, subject to the specific program and property requirements.
That can be relevant whether you're searching around California and Hollywood, considering Mechanicsville, looking around Waldorf or La Plata, or comparing homes in Lusby and Prince Frederick.
The key is to check eligibility before assuming you qualify—or assuming that you do not.
What Is the Minimum Credit Score Required to Buy a House in Maryland?
There is no single credit score that determines whether every person can buy a house in Maryland.
Credit requirements depend on factors such as the mortgage product, lender, underwriting method, mortgage insurer, down payment, and any assistance program being used. HUD similarly advises consumers that mortgage qualification requirements vary among loan types.
For the Maryland Mortgage Program specifically, credit-score requirements are part of program eligibility, and individual products may impose additional requirements.
This distinction matters because a minimum associated with one program should not be presented as the universal minimum credit score required to buy any home in Maryland.
HUD also explains that affordability depends on multiple factors, including income, credit rating, monthly expenses, down payment, and the interest rate.
Rather than ruling yourself out based on a number you found online, consider discussing your full financial picture with an appropriate lender. A lender can explain which mortgage products you may currently qualify for and what steps could improve your options.
How Much Income Do You Need to Buy a House in Maryland?
There is no single annual income that everyone must earn to buy a home in Maryland.
The income needed to comfortably purchase a particular property depends on variables such as:
-
Purchase price
-
Down payment
-
Current mortgage rates
-
Existing monthly debts
-
Property taxes
-
Homeowners insurance
-
Mortgage insurance, when applicable
-
HOA or condominium fees, when applicable
-
Loan type and underwriting requirements
Someone purchasing a lower-priced property with limited monthly debt can have a very different qualification profile from someone purchasing a more expensive property while carrying significant existing obligations.
Maryland Mortgage Program eligibility adds another consideration: household-income limits.
Those limits vary by jurisdiction and program, and Maryland updates them periodically. For 2026, Maryland announced updated MMP income and purchase-price limits effective June 24, 2026. Certain specialized programs also use Area Median Income thresholds.
So when someone asks, “How much income do I need to buy a house in Maryland?” the more useful question is:
How much home can I reasonably afford based on my income, debts, available funds, financing options, and total monthly housing expenses?
A mortgage preapproval can help turn those variables into a more useful price range before you begin seriously touring properties.
How to Prepare as a First-Time Home Buyer in Southern Maryland
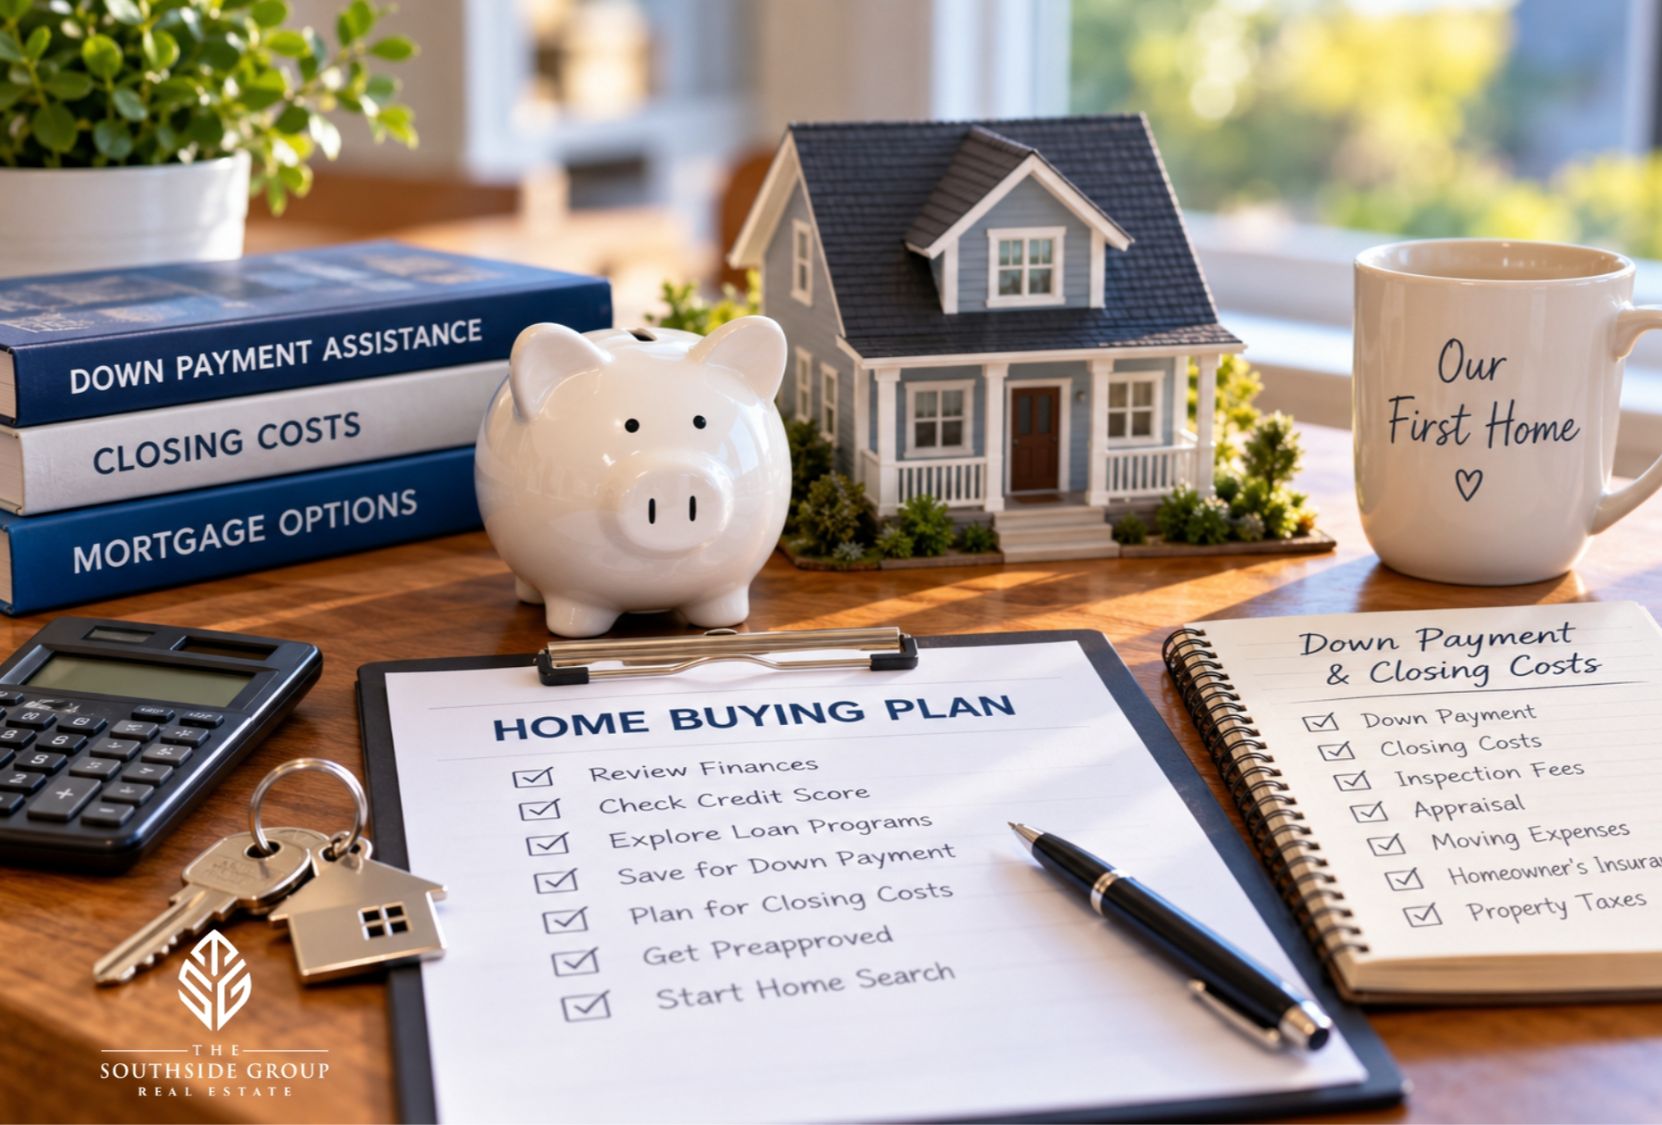
Buying your first home—or your first home after several years of renting—can feel complicated. Breaking the process into manageable steps can make it easier.
Start by reviewing your income, recurring debts, savings, and credit profile. Then speak with an appropriate mortgage professional about available loan programs and whether Maryland Mortgage Program assistance may apply to your circumstances.
If you plan to use MMP, approved homebuyer education is required for programs such as 1st Time Advantage and Flex. Maryland also generally recommends homebuyer education or housing counseling for residential mortgage applicants before signing documents that commit them to a loan.
Once you understand your financing options, obtain a preapproval and establish a home-search budget based on what you are comfortable paying—not simply the highest amount you might be approved to borrow.
Then you can begin comparing properties and communities across Southern Maryland.
Why Work With a Southern Maryland Real Estate Expert
Understanding financing is only one part of purchasing a home. Local market knowledge can also help buyers compare properties, communities, asking prices, contract terms, and available inventory.
Our Southern Maryland real estate coverage includes St. Mary's County, Charles County, and Calvert County, with buyers searching communities such as Waldorf, Hollywood, La Plata, Lexington Park, Leonardtown, Mechanicsville, and California.
Working with experienced local professionals gives you a resource for understanding the home-search and purchase process while your lender handles mortgage qualification and program eligibility.
If you're searching for Top Real Estate Agents & Realtors in Southern Maryland or wondering How to Find a Local Realtor Near Me, experience in the specific communities you're considering matters. Our team focuses on providing local knowledge, responsive guidance, and practical information throughout the home-buying process.
If you're wondering whether now is the right time to start your search, contact our team today to discuss what you're looking for.
You may be closer to qualifying as a first-time buyer than you realized. Start exploring Southern Maryland opportunities and Browse Homes for Sale.
Program guidelines, income limits, loan requirements, and assistance availability can change. This article is for general educational purposes and is not mortgage, legal, tax, or financial advice. Confirm current eligibility and loan terms with the applicable program administrator and an approved lender.
FROM OUR BLOG
How Real Estate Agents Can Generate Business From Their Database
Many real estate agents spend a significant amount of time searching for new leads, exploring marketing strategies, and finding ways to grow their businesses. But what if some of your next opportunities are already sitting in your phone, email contacts, or CRM? Your real estate database is more than
Golden Beach Real Estate Market Update | October 19, 2026
The Golden Beach real estate market update for October 19, 2026, highlights a limited selection of available homes and an equal number of properties currently under contract. According to the market figures supplied for this update, Golden Beach in Mechanicsville, Maryland, has just 3 active listing
How Long Does It Take to Buy a House?
How Long Does It Take to Buy a House? What Southern Maryland Buyers Should Know How long does it take to buy a house in Southern Maryland? For most buyers, the process is better measured in stages than by one fixed number of days. You need time to prepare financially, get pre-approved, find the righ